

This article will discuss how to value a company using the residual income valuation model. Residual income is the earnings a company generates in excess of its required return on equity capital. By discounting future residual incomes to their present value, investors can estimate a company's intrinsic value. This valuation approach is particularly useful for companies with no dividends, unpredictable dividend patterns, or negative free cash flows that are expected to turn positive.
This article will explain the residual income and economic value added financial metrics, detailing the methodology and formulas underlying both models as well as three different intrinsic value models. We'll also provide a step-by-step example using a real-world company to demonstrate how to calculate and interpret the model's output, with a free Excel template included. Finally, we'll discuss the model's limitations and key considerations when applying it in real-world scenarios.
Residual Income Valuation Explained
The residual income model (RIM), also known as the abnormal earnings model, estimates a company's intrinsic value by calculating the income generated after accounting for the cost of equity. The economic value added (EVA) model, while similar, includes the cost of all capital, including debt and preferred stock. The RIM concept stems from the works of Edwards and Bell (1961), Peasnell (1982), and Ohlson (1995), who developed and refined the concept of residual income as a measure of a company's economic profitability.
The premise of the residual income valuation model is that a company's intrinsic value equals the sum of its book value and the present value of its expected future residual incomes. Residual income is defined as the earnings a company generates in excess of its required return on equity capital. In other words, it's the profit left over after accounting for the opportunity cost of the equity capital employed by the company.
One key benefit of the residual income model is that it addresses a limitation of traditional accounting practices by explicitly incorporating the cost of equity capital, providing a more accurate assessment of a company's economic profitability. A company's income statement accounts for the cost of debt financing through interest expenses but doesn't consider the cost of equity financing. This can lead to a company reporting positive net income but failing to create value for shareholders if its earnings don't exceed the required return on equity.
Given its focus on economic profitability, the residual income valuation approach is particularly useful for:
- Companies that don't pay dividends or have unpredictable dividend patterns.
- Companies that have yet to generate positive free cash flows but are expected to do so in the future.
- Companies that may have positive free cash flows, but they are very unpredictable.
- Situations where there's uncertainty in forecasting terminal values.
In these cases, the residual income model can be a valuable alternative to the dividend discount model (DDM) and discounted cash flow (DCF) methods. However, if a company has stable, predictable dividends or cash flows, it may be more appropriate to use one of these other valuation approaches.
It's important to recognize that the residual income approach, like many valuation models, relies on forward-looking assumptions and estimates that can be influenced by biases and uncertainties. The accuracy of the model depends on the reliability of the financial data and the reasonableness of the assumptions used, such as projected earnings, cost of equity, and growth rates.
How to Calculate and Interpret Residual Income and Economic Value Added
Before discussing the intrinsic value formulas, it's important to understand residual income (RI) and economic value added (EVA). These measures provide valuable insights into a company's profitability and value creation by considering the cost of capital employed.
Residual income focuses on the excess return available to common shareholders after accounting for the cost of equity capital, while economic value added takes a broader view by considering the cost of all capital, including debt and preferred stock.
Understanding these concepts is fundamental to applying the residual income valuation model effectively and interpreting the results accurately.
Residual Income
Residual income (RI) measures a company's profitability after considering the opportunity cost of the equity capital employed. It represents the excess earnings generated by a company beyond what is required to compensate equity investors for their investment.
The formula for calculating residual income is shown below:
RIt = NIt - (re × BVt-1)
where:
- RIt = residual income at time t
- NIt = net income at time t
- re = cost of equity
- BVt-1 = book value of equity at the end of the previous period (t - 1)
To better understand the residual income formula, let's discuss each input in more detail:
- Net Income (NIt): Company's total earnings or profit, calculated by subtracting total expenses from total revenues. It's found on the company's income statement and represents the bottom line profit attributable to shareholders.
- Book Value of Equity (BVt-1): Also known as shareholders' equity, it's the difference between a company's total assets and total liabilities, as reported on its balance sheet. In other words, it represents the accounting value of the equity that belongs to shareholders. The subscript "t-1" indicates that the book value is measured at the end of the previous period, providing the starting value for calculating residual income in the current period t.
- Cost of Equity (re): Required rate of return that equity investors expect to earn for investing in a company. It's typically estimated using the Capital Asset Pricing Model (CAPM), which considers the market's risk-free rate and expected return, as well as the company's beta (a measure of its systematic risk).
For reference, the formula below shows the CAPM calculation:
re = rf + β × (rm - rf)
where:
- re = cost of equity
- rf = risk-free rate
- β = beta
- rm = expected market return
Related: How to Calculate and Interpret the Capital Asset Pricing Model (CAPM)
The CAPM calculates the expected return on an investment for equity investors by adding the risk-free rate (rf) to the product of the investment's beta (β) and the market risk premium (rm - rf). It helps determine the appropriate required return for equity holders based on the asset's relative risk compared to the overall market.
A key component of the residual income formula is the equity charge, which represents the cost of equity capital. In other words, the equity charge is the minimum return that a company must earn to satisfy its equity investors. It's calculated by multiplying the cost of equity by the book value of equity at the beginning of the period (re × BVt-1).
By comparing a company's net income to its equity charge, the residual income metric provides insight into whether the company is generating returns that exceed the cost of equity capital. A positive residual income indicates that the company is creating value for its shareholders, while a negative residual income suggests that the company is destroying shareholder value.
It's important to note that a company can have a positive net income but a negative residual income. This situation can occur when the company's earnings, although positive, do not exceed the opportunity cost of the equity capital invested by shareholders.
For example, if a company has net income of $1M, book value of equity of $10M, and cost of equity of 12%, the residual income would be:
RI = $1M - (12% * $10M) --> -$200K
In this case, the company is profitable from an accounting perspective but is not generating enough returns to cover the opportunity cost of the equity capital invested. Shareholders could've earned a higher return by investing their money elsewhere, given the level of risk associated with the company. As a result, the company is not creating economic value for its shareholders, despite having a positive net income.
Economic Value Added
Economic value added (EVA) measures a company's profitability after considering the opportunity cost of the total capital employed. Therefore, while residual income focuses solely on the cost of equity, EVA takes into account the total cost of capital, including debt, equity, and preferred stock (if applicable).
The formula for calculating EVA is shown below:
EVAt = NOPATt - (WACC × ICt-1)
where:
- EVAt = economic value added at time t
- NOPATt = net operating profit after taxes at time t
- WACC = weighted average cost of capital
- ICt-1 = invested capital at the end of the previous period (t - 1)
To better understand the EVA formula, let's discuss each input in more detail:
- Net Operating Profit After Taxes (NOPATt): NOPAT represents a company's operating profit after accounting for taxes. To calculate NOPAT, start with the company's operating profit (also known as earnings before interest and taxes, or EBIT) and subtract the taxes paid on that profit, reflecting the company's effective tax rate. This measure provides a clear view of the company's operating efficiency and profitability, independent of its capital structure and tax strategies.
- Invested Capital (ICt-1): Invested capital is the total cash invested in a company over its life, from any financing source. It includes equity, debt, and preferred shares. To calculate it, add the book values of equity, debt, and preferred shares, which can be found on the company's balance sheet. Like the book value of equity in the residual income formula, invested capital is measured at the end of the previous period (t-1) to calculate EVA in the current period t.
- Weighted Average Cost of Capital (WACC): Represents the average cost of all sources of capital, including equity, debt, and preferred shares, weighted by their respective proportions in the company's capital structure. The WACC is essentially the minimum return that a company must earn on its invested capital to satisfy all its capital providers.
For reference, the formula below shows the WACC calculation:
WACC = (wd × rd × (1 - t)) + (wp × rp) + (we × re)
where:
- w = weights for each capital component
- r = cost (aka required rate of return) for each capital component
- t = tax rate
- d = debt
- p = preferred shares
- e = equity
Related: How to Calculate and Interpret the Capital Asset Pricing Model (CAPM)
By comparing NOPAT to the total cost of capital employed (WACC × ICt-1), EVA measures the excess return generated by the company. A positive EVA indicates that the company is creating value for its investors by generating returns above its cost of capital, while a negative EVA suggests that the company is destroying value.
Similar to residual income, a company can have positive operating profit but negative EVA if its returns do not cover the total cost of capital.
For example, if a company has NOPAT of $2M, invested capital of $20M, and a WACC of 12%, the EVA would be:
EVA = $2M - (12% × $20M) --> -$400K
In this case, although the company is generating operating profits, it's not creating economic value for its capital providers (equity investors, debt holders, and preferred shareholders) because the returns are not sufficient to cover the total cost of the capital employed.
Residual Income or Economic Value Added for Stock Valuations
When it comes to stock valuation, the choice between residual income (RI) and economic value added (EVA) depends on the investor's focus and the company's capital structure, as detailed below:
- Residual Income (RI): More relevant for common stock investors as it directly measures the excess return available to shareholders after accounting for the cost of equity capital. It aligns with their primary concern of maximizing return on investment.
- Economic Value Added (EVA): Provides a broader view of a company's value creation by considering the costs and returns for all capital providers, including debt holders and preferred shareholders. While this perspective is valuable for assessing overall firm performance, it may be less pertinent for common stock investors. However, EVA can still indirectly impact common stock value by reflecting the company's ability to create value for all stakeholders.
In summary, residual income is more focused on equity valuation and directly relevant to common stockholders, while EVA offers a broader view of a company's overall financial performance. Investors may need to consider both when making investment decisions, but for the purposes of this article, we'll focus on the residual income valuation model.
Residual Income Valuation Models
Residual income valuation models estimate the intrinsic value of a company's stock by focusing on the economic profitability of a company, considering the excess income generated after accounting for the cost of equity capital.
In this section, we'll discuss three distinct residual income valuation models: the residual income model (RIM), the perpetual growth RIM, and the two-stage RIM. Each model offers unique advantages and is suitable for different types of companies and growth scenarios.
By understanding and applying these models, investors can gain valuable insights into a company's intrinsic value and make more informed investment decisions.
Residual Income Model
The residual income model (RIM) estimates the intrinsic/fair value of a company's stock by summing two key components:
- Current book value of the firm.
- Present value of all future residual earnings.
Thus, by discounting future residual incomes to their present value and adding them to the current book value of equity, investors can estimate the intrinsic/fair value of a company's stock.
Here's how the RIM is expressed as a formula:
where:
- P0 = stock's fair value (at year 0)
- BVPS0 = current per-share book value of equity
- RIt = expected per-share residual income, calculated as either "EPSt - (re × BVPSt-1)" or "(ROEt - re) × BVPSt−1"
- re = cost of equity
In this formula, "BVPS0" represents the current per-share book value of equity, which is the company's total equity divided by the number of outstanding shares. This information can be found on the company's balance sheet. The sigma (∑) symbol represents the sum of the series of future residual incomes, discounted back to their present value using the cost of equity (re), which can be estimated using models like the CAPM (as previously discussed). The infinity (∞) symbol above the sigma indicates that the series continues indefinitely into the future.
"RIt" is the expected per-share residual income for each future period t. It can be calculated using either of the following formulas:
- EPSt - (re × BVt-1): This formula calculates residual income by subtracting the equity charge (re × BVt-1) from the expected earnings per share (EPSt) for each period t. The equity charge represents the cost of equity capital multiplied by the per-share book value of equity at the end of the previous period (t - 1). Note that earnings per share (EPS) is used instead of net income to represent the formula's per-share basis .
- (ROEt - re) × BVt-1: This formula calculates residual income by multiplying the difference between the expected return on equity (ROEt) and the cost of equity (re) by the per-share book value of equity at the end of the previous period (t - 1).
The choice between the two formulas for calculating "RIt" depends on several factors, as discussed below. Regardless, both formulas are mathematically equivalent and will yield the same result.
If the company provides guidance on expected EPS, the first formula (EPSt - (re × BVPSt-1)) can be used, as it directly incorporates the expected EPS. This is suitable for companies with varying profitability or those undergoing significant changes.
Alternatively, if the investor has estimates of the company's future ROE, the second formula ((ROEt - re) × BVPSt-1) may be easier to implement, assuming a constant ROE over time. This is more common in mature, stable companies with consistent profitability.
Get Our 50-Question Stock Analysis Checklist!
After researching hundreds of stocks, we built this 50-question checklist to guide your analysis and help you avoid costly mistakes.
Download ChecklistIn summary, the first formula is preferable for understanding earnings relative to book value, while the second formula is useful for assessing how effectively a company uses its equity to generate profits.
Perpetual Growth Residual Income Model
Now, if we assume that a company's earnings per share (EPS) grows at a constant rate into perpetuity, we can simplify the RIM formula as follows:
where:
- P0 = stock's fair value (at year 0)
- BVPS0 = current per-share book value of equity
- EPS0 = current earnings per share
- g = perpetual growth rate of earnings
- re = cost of equity
This simplified formula, known as the perpetual growth residual income model (RIM), assumes that residual income grows at a constant rate, enabling the application of the perpetuity formula to calculate the present value of future residual incomes.
Note that for this formula to be valid, two important conditions must be met for the perpetual growth rate (r):
- Perpetual Growth Rate Less Than Cost of Equity: The perpetual growth rate (g) must be less than the cost of equity (re). If the growth rate is equal to or higher than the cost of equity, the denominator (re - g) will be zero or negative, resulting in a misleading or undefined valuation. This is because a company cannot sustain a growth rate that exceeds its cost of equity indefinitely, as it would imply that the company can create value without any additional capital investment.
- Perpetual Growth Rate Less Than Nominal GDP Growth Rate: The perpetual growth rate (g) should also be lower than the nominal GDP growth rate of the country in which the company resides. This ensures that the company's growth rate is realistic and sustainable within the broader economic context. If a company's growth rate were to exceed the nominal GDP growth rate, it would imply that the company could outpace the entire economy indefinitely, which is unrealistic.
The primary difference between the standard RIM and the perpetual growth RIM is the assumption of constant growth in earnings. While the standard model allows for varying growth rates and requires forecasting residual income for each future period, the perpetual growth model simplifies the calculation by assuming a constant growth rate, making it more suitable for companies with more stable and predictable earnings growth.
Perpetual Growth RIM Relationship to the Dividend Discount Model (DDM)
Notably, the perpetual growth residual income model (RIM) and the dividend discount model (DDM) are intrinsically linked through the clean surplus relationship (CSR). The CSR is an accounting identity that connects a company's book value of equity, earnings, and dividends, as shown in the formula below:
BVPSt = BVPSt-1 + EPSt - DPSt
where:
- BVPSt = per-share book value of equity at the end of period t
- BVPSt-1 = per-share book value of equity at the end of the previous period (t - 1)
- EPSt = earnings per share during period t
- DPSt = dividend per share paid during period t
The CSR states that the change in a company's book value of equity from one period to the next is equal to its earnings minus the dividends paid out during that period.
If we assume that a company pays out a constant proportion of its earnings as dividends (i.e., maintains a constant dividend payout ratio (DPR)), then both earnings and book value will grow at the same constant rate. Under this assumption, the perpetual growth RIM and the perpetual growth DDM (aka Gordon Growth Model (GGM)), will yield the same estimate of intrinsic value.
For reference, the GGM formula is shown below:
where:
- P0 = stock's fair value (at year 0)
- DPS0 = annual dividends per share (at year 0)
- g = perpetual dividend growth rate
- re = cost of equity
Related: How to Apply the Gordon Growth Model (GGM) for Dividend Discount Valuation
However, when the CSR doesn't hold or when a company's book value and return on equity (ROE) are unpredictable, the perpetual growth RIM and DDM may diverge in their intrinsic value estimates. This divergence occurs because the RIM and DDM focus on different aspects of a company's financial performance.
The DDM emphasizes dividends, which represent the actual cash flows received by shareholders. In contrast, the RIM focuses on residual income, which measures a company's ability to generate returns above its cost of equity capital, regardless of the actual cash distributed to shareholders.
This difference in focus makes the RIM more suitable for companies with unpredictable earnings and dividend patterns, as it captures the economic profitability of the company rather than relying solely on the consistency of dividend payments. Consequently, when the CSR assumption is violated, or when book value and ROE are difficult to predict, the RIM can provide a more comprehensive assessment of a company's intrinsic value compared to the DDM.
Two-Stage Residual Income Model
The two-stage residual income model (RIM) is an extension of the standard residual income model (RIM) that allows for a more detailed analysis of a company's future prospects. This model is particularly useful when a company is expected to experience a period of high or low growth followed by a period of stable growth.
In the two-stage RIM, the valuation is divided into two distinct periods:
- Explicit Forecast Period: This is the period for which detailed residual income forecasts are made, typically ranging from 3 to 10 years, depending on the company's characteristics and the investor's confidence in the forecasts.
- Terminal Period: This period begins immediately after the explicit forecast period and typically assumes a perpetual growth rate in residual income. Other possible assumptions include residual income remaining at a constant positive level, decreasing to zero, or stabilizing at a long-term average.
Here's how the two-stage RIM is expressed as a formula:
where:
- P0 = stock's fair value (at year 0)
- BVPS0 = current per-share book value of equity
- BVPSt = expected per-share book value of equity at any time t
- re = cost of equity
- EPSt = expected earnings per share for period t
- RIt = expected per-share residual income, calculated as either "EPSt - (re × BVPSt-1)" or "(ROEt - re) × BVPSt−1"
- ROEt = return on equity at time t
- PT = expected per-share price at terminal time T
- BVPST = expected per-share book value at terminal time T
The main difference between the two-stage RIM and the standard RIM lies in the explicit consideration of two distinct growth periods. The two-stage model introduces a terminal value component that captures the value of the company beyond the explicit forecast period, assuming a stable growth rate in residual income. This allows investors to make more detailed assumptions about a company's future growth prospects and incorporate them into the valuation process.
Given the flexibility to model different growth periods, investors should consider using the two-stage RIM when:
- A company is expected to experience a period of high or low growth followed by a period of stable growth.
- The investor has detailed information about a company's future prospects and can make reliable forecasts for the explicit forecast period.
- A company's growth prospects are expected to change significantly after the explicit forecast period.
Notably, unlike the discounted cash flow (DCF) model, the terminal value in the two-stage RIM approach does not constitute a relatively large portion of the intrinsic value. This is because the RIM accounts for economic profitability by recognizing the value created by the company above the required return on equity immediately.
In other words, the model directly incorporates the current and near-term excess earnings (residual income) rather than relying heavily on future cash flows or dividends, which can be more volatile and harder to predict in the long term. This immediate recognition of residual income reduces the relative weight of the terminal value in the overall valuation.
Now, when considering the terminal value component, investors must make assumptions about the continuing residual income during the terminal period. Some common assumptions include:
- The residual income grows at a perpetual rate indefinitely.
- The residual income remains at a constant positive level indefinitely.
- The residual income decreases to zero after the terminal year.
- The residual income gradually declines to zero as the company's ROE converges to its cost of equity (re) over time.
- The residual income stabilizes at a level that reflects the company's long-term average ROE.
This decision is typically made based on the company's historical performance, industry conditions, and the investor's expectations for the company's future profitability.
If a constant perpetual growth for the terminal value is assumed, then like the perpetual growth RIM, the terminal value perpetual growth in the two-stage RIM follows the same principles. The perpetual growth rate included in the "PT" calculation must be below the cost of equity (re) and the nominal GDP growth rate of the economy in which the company predominantly resides.
In summary, the two-stage RIM can be useful for investors seeking to value companies with varying growth prospects. By incorporating detailed forecasts during the explicit forecast period and making reasonable assumptions about the terminal period, investors can gain a more comprehensive understanding of a company's intrinsic value and make better-informed investment decisions.
Residual Income Valuation Example
To demonstrate how to value stocks using the residual income model (RIM), specifically the two-stage model since it's comprehensive and potentially more accurate, we'll use Super Micro Computer (SMCI) as our example company. Super Micro Computer designs, manufactures, and sells high-performance server and storage systems for data centers, cloud computing, enterprise IT, and big data analytics markets.
Super Micro Computer is a suitable candidate for the two-stage RIM because it does not pay dividends and its free cash flow (FCF) has been irregular over recent years, including the trailing twelve months (TTM). However, the company has been consistently profitable for the last 10+ years, making it a good fit for the residual income valuation approach, which focuses on economic profitability rather than consistent dividends or cash flows.
Here are the ten steps investors can follow to calculate the two-stage RIM for any company, as explained in greater detail in the following sections:
- Step #1: Gather Necessary Financial Data
- Step #2: Calculate or Find the Current Book Value Per Share (BVPS0)
- Step #3: Calculate the Cost of Equity Using the Capital Asset Pricing Model (CAPM)
- Step #4: Determine the Number of Years in the Explicit Forecast Period
- Step #5: Forecast Earnings Per Share (EPS) and Dividends Per Share (DPS)
- Step #6: Forecast Book Value Per Share (BVPS)
- Step #7: Calculate Residual Income for Each Forecast Year
- Step #8: Calculate the Terminal Residual Value
- Step #9: Calculate the Present Value of Residual Income
- Step #10: Calculate and Interpret the Two-Stage Residual Income Model (RIM)
Step #1: Gather Necessary Financial Data
To calculate the two-stage RIM for any company, you'll need to gather relevant financial data from the income statement and balance sheet. Financial statements can be sourced from the company's 10-K annual report, which can be found via the Securities and Exchange Commission (SEC) or the company's investor relations pages.
Income Statement
The income statement is a financial report that details a company's revenues, expenses, and net profit (or loss) over a specific period.
Related: How to Effectively Read and Analyze an Income Statement
From the income statement, we'll locate the following figures:
- Diluted Earnings Per Share (EPS): Calculated by dividing net income by the total number of diluted shares outstanding, which includes the impact of potential dilutive securities such as stock options, warrants, and convertible bonds.
- Diluted Shares Outstanding: The total number of shares that would be outstanding if all potential sources of conversion, such as convertible bonds and stock options, were exercised.
Note that we're using diluted figures instead of basic ones because diluted EPS and shares outstanding account for the potential impact of dilutive securities (e.g., stock options, warrants, convertible securities, etc.) on earnings and ownership. This approach offers a more conservative and accurate assessment of the company's financial performance and value per share.
Here's Super Micro Computer's income statement with these two financials outlined:

Thus, in FY 2023, Super Micro Computer reported a diluted EPS of $11.43, with 55,970K diluted shares outstanding.
Balance Sheet
The balance sheet provides a snapshot of a company's financial position at a specific point in time, showing assets, liabilities, and shareholders' equity.
Related: How to Effectively Read and Analyze a Balance Sheet
From the balance sheet, the only financial figure required is the company's total shareholders' equity, which represents the residual interest in the assets of the company after deducting all its liabilities. This is also called the book value of equity, as it reflects the accounting value of the company's equity on its balance sheet.
Here's Super Micro Computer's balance sheet with total shareholders' equity outlined:
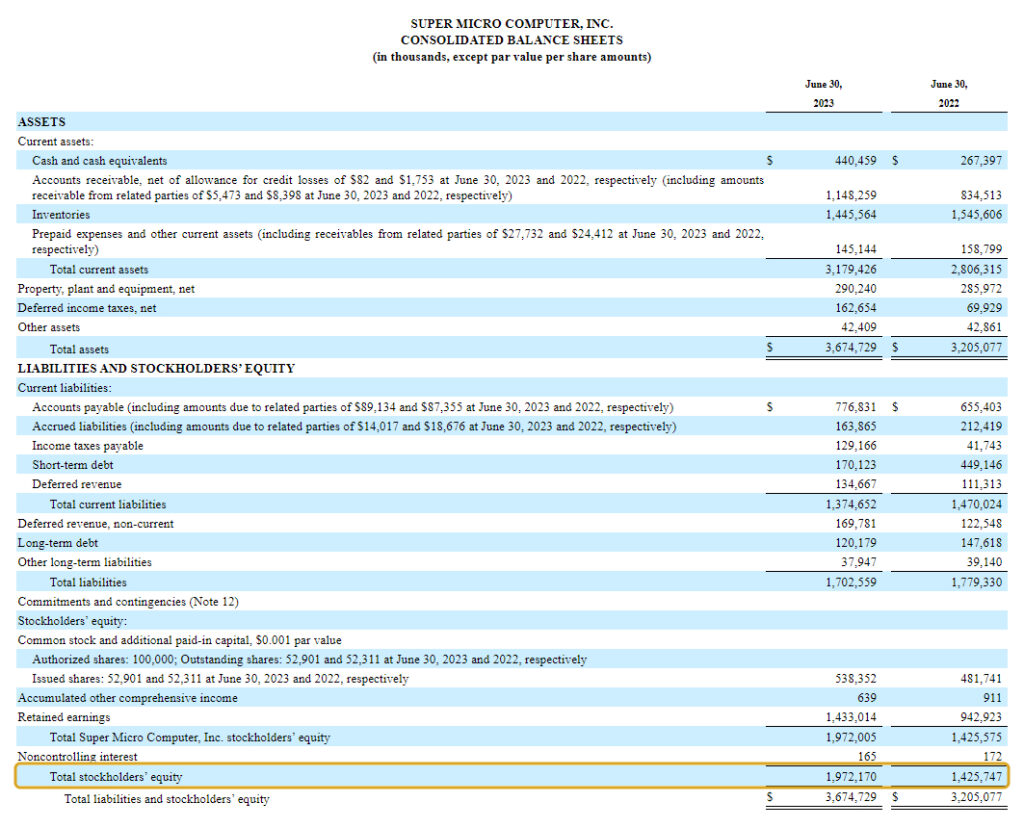
Thus, in FY 2023, Super Micro Computer reported total shareholders' equity of $1,972,170K.
Step #2: Calculate or Find the Current Book Value Per Share (BVPS0)
After gathering the necessary financial data, the next step in the two-stage RIM is to calculate the company's current book value per share (BVPS0). This metric represents the starting point for estimating the company's intrinsic value. BVPS can also be found on various stock market data websites.
The standard formula for calculating BVPS is shown below:
BVPS = Total Shareholders' Equity / Total Shares Outstanding
However, for the purpose of the RIM, we'll use the weighted diluted shares outstanding instead of the total shares outstanding. This approach ensures consistency with the diluted EPS figure used in the model and accounts for the potential impact of dilutive securities on the company's ownership structure.
Using the information from Step #1, we can calculate Super Micro Computer's BVPS0 for FY 2023 as follows:
BVPS0 [SMCI; FY 2023] = $1,972,170K / 55,970K --> $35.24
This means that as of June 30, 2023 (the end of FY 2023), Super Micro Computer's BVPS0 was $35.24. In other words, if the company were to liquidate all its assets and pay off all its liabilities, each share would be worth $35.24.
It's important to note that BVPS is an accounting measure and does not necessarily reflect the market value of the company's shares. However, it serves as a useful starting point for estimating the company's intrinsic value using the RIM.
Step #3: Calculate the Cost of Equity Using the Capital Asset Pricing Model (CAPM)
The next step in the two-stage RIM valuation is to calculate the cost of equity (re), also known as the required rate of return or discount rate, using the Capital Asset Pricing Model (CAPM). Calculating the CAPM for Super Micro Computer provides insight into the implied risk and expected return for equity shareholders, based on the model's assumption that higher risks are associated with higher returns.
The CAPM formula is shown below (again):
re = rf + β × (rm - rf)
where:
- re = cost of equity
- rf = risk-free rate
- β = beta
- rm = expected market return
The CAPM calculates the expected return on an investment by adding the risk-free rate of return to the product of the stock's beta and the difference between the expected market return and the risk-free rate (aka the "market risk premium").
To calculate the CAPM for Super Micro Computer, we need to determine three key inputs:
- Risk-Free Rate (rf): This is often represented by the yield on the 10-year U.S. Treasury Note, known for its security and low default risk, guaranteed by the U.S. government. The risk-free rate also provides a baseline for comparing the risks of more speculative investments. Currently, this rate is 4.43%.
- Beta (β): Beta measures the stock's volatility relative to the overall market. A beta greater than 1 indicates higher volatility than the market, while a beta less than 1 indicates lower volatility. Super Micro Computer's 5-year monthly beta, available on financial websites like Yahoo Finance, is currently 1.23.
- Expected Market Return (rm): The expected market return is typically assumed to be ~10%, reflecting the long-term average annual return of the market, as represented by the S&P 500 Index.
Using these inputs, we can calculate the CAPM for Super Micro Computer as follows:
re [SMCI] = 4.43% + 1.23 × (10% - 4.43%) --> 11.28%
This CAPM calculation for Super Micro Computer yields an expected return of 11.28%. This represents the cost of equity (re), suggesting that any investment in the company should aim for at least this rate of return to compensate for the associated risks.
Step #4: Determine the Number of Years in the Explicit Forecast Period
The next step in applying the two-stage RIM is to determine the number of years for which you will provide detailed residual income forecasts, known as the explicit forecast period. This period typically ranges from 3 to 10 years, depending on the company's characteristics, the investor's confidence in their forecasts, and the stability of the company's growth prospects.
For Super Micro Computer, let's assume an explicit forecast period of 5 years, given the company's recent strong performance and for demonstration purposes.
After the explicit forecast period, our model will assume a stable growth rate for the company's residual income, which is captured in the terminal value calculation.
Step #5: Forecast Earnings Per Share (EPS) and Dividends Per Share (DPS)
To apply the two-stage RIM, it's necessary to forecast the company's future earnings per share (EPS) and, if applicable, dividends per share (DPS). These forecasts are needed for calculating the company's present value of expected residual income.
EPS forecasts can be based on various sources, such as:
- Analyst Estimates: Many financial websites and databases provide consensus analyst estimates for a company's future EPS.
- Investor's Assumptions: Investors can develop their own EPS forecasts based on their analysis of the company's financial statements, industry trends, and growth prospects.
- Historical Growth Rates: Investors can also use the company's historical EPS growth rates as a starting point for their forecasts, adjusting them based on expected changes in the company's future performance.
For Super Micro Computer, we'll base our EPS forecasts for the first three years (FY 2024, 2025, and 2026) on analyst estimates sourced from Koyfin. For years 4 and 5, we'll assume that EPS grows at 15% each year, given that analyst estimates suggest slowing growth.
The EPS forecasts for Super Micro Computer are as follows:
- FY 2024: $22.38
- FY 2025: $32.45
- FY 2026: $40.52
- FY 2027: $46.60 (15% growth from FY 2026)
- FY 2028: $53.59 (15% growth from FY 2027)
In addition to EPS, investors may also need to forecast DPS if the company currently pays dividends or is expected to start paying dividends during the forecast period. DPS forecasts can be based on the company's historical dividend growth rates, dividend payout ratios, or management's guidance on future dividend policy.
To forecast DPS using the dividend payout ratio (DPR) method, investors can multiply the forecasted DPR by the forecasted EPS, as this reflects the proportion of earnings that a company intends to distribute as dividends. This formula is shown below:
Forecasted DPS = Forecasted DPR × Forecasted EPS
The forecasted DPR is based on the company's historical payout ratios, investor assumptions, or management's stated dividend policy. Forecasted EPS is determined using the methods discussed earlier, such as analyst estimates, investor insights, or historical growth rates.
Since Super Micro Computer is not a dividend-paying company and there's no indication that it will start paying dividends in the near future, we'll assume that DPS remains at $0 throughout the forecast period.
Step #6: Forecast Book Value Per Share (BVPS)
To calculate the residual income for each year in the explicit forecast period, investors need to forecast the company's book value per share (BVPS). The BVPS for a given year is calculated using the clean surplus relationship (CSR), as discussed earlier in this article, which states that the book value of equity increases by the company's earnings and decreases by the dividends paid out to shareholders.
The formula for calculating the forecasted BVPS, which is based on the CSR, is shown below (again):
BVPSt = BVPSt-1 + EPSt - DPSt
where:
- BVPSt = per-share book value of equity at the end of period t
- BVPSt-1 = per-share book value of equity at the end of the previous period (t - 1)
- EPSt = earnings per share during period t
- DPSt = dividend per share paid during period t
For our Super Micro Computer example, let's calculate the forecasted BVPS for FY 2024. From Step #2, we know that the current BVPS0 (FY 2023) is $35.24. We also have the forecasted EPS for FY 2024 from Step #5, which is $22.38, and the assumed DPS of $0 since the company doesn't pay dividends.
Plugging these values into the formula, we get:
BVPS2024 = BVPS2023 + EPS2024 - DPS2024
BVPS [SMCI; FY 2024] = $35.24 + $22.38 - $0 --> $57.62
Therefore, based on our forecasts, Super Micro Computer's BVPS is expected to increase from $35.24 in FY 2023 to $57.62 in FY 2024.
Investors should repeat this process for each year in the explicit forecast period, using the forecasted EPS and DPS values and the previous year's BVPS to calculate each year's BVPS.
Step #7: Calculate Residual Income for Each Forecast Year
With the forecasted EPS, DPS, and BVPS values, investors can now calculate the residual income for each year in the explicit forecast period. Residual income is the earnings a company generates in excess of its required return on equity capital. It can be calculated using one of two formulas (as previously discussed):
- RIt = EPSt - (re × BVPSt-1)
- RIt = (ROEt - re) × BVPSt-1
where:
- RIt = residual income in year t
- EPSt = expected earnings per share for period t
- re = cost of equity
- BVPSt-1 = per-share book value of equity at the end of the previous period (t - 1)
- ROEt = return on equity in year t, calculated as "EPSt / BVPSt-1"
These two approaches to calculating residual income are algebraically equivalent and will always lead to the same result. The first approach focuses on the direct comparison between the earnings per share (EPSt) and the equity charge (re × BVPSt-1), while the second approach highlights the difference between the ROE and the cost of equity (re).
For our Super Micro Computer example, we'll use the first formula. Let's calculate the residual income for FY 2024:
RI2024 = EPS2024 - (re × BVPS2023)
RI [SMCI; FY 2024] = $22.38 - (11.28% × $35.24) --> $18.40
To confirm this result using the second approach, begin by calculating the forecasted ROE:
ROE2024 = EPS2024 / BVPS2023
ROE [SMCI; FY 2024] = $22.38 / $35.24 --> 63.51%
Then, complete the second residual income formula approach:
RI2024 = (ROE2024 - re) × BVPS2023
RI [SMCI; FY 2024] = (63.51% - 11.28%) × $35.24 --> $18.40
As you can see, both approaches lead to the same residual income of $18.40 per share for FY 2024. This means that Super Micro Computer is expected to generate $18.40 per share in excess of its required return on equity capital.
Investors should repeat this process for each year in the explicit forecast period using the forecasted EPS and the previous year's BVPS to calculate the residual income. These residual income values will be discounted to present value in Step #9, while the final year's residual income will be calculated using the terminal value approach, as discussed in the next step, Step #8.
Step #8: Calculate the Terminal Residual Value
The terminal value represents the present value of all future residual incomes beyond the explicit forecast period. In the two-stage RIM, the terminal value is calculated using the following formula:
Terminal Value = (PT - BVPST) / (1 + re)T
where:
- PT = expected per-share price at terminal time T
- BVPST = expected per-share book value at terminal time T
- re = cost of equity
- T = number of years in the explicit forecast period
In this step, we'll focus on calculating the difference between the expected per-share price at the terminal time T (PT) and the expected BVPS at the terminal time T (BVPST), which is a key component of the terminal value in the two-stage RIM. The discounting to present value process "(1 + re)T" will be completed in the next step, Step #9.
To calculate "PT," we'll use the perpetual growth formula, which is derived from the Gordon Growth Model (GGM). The GGM assumes that a company's dividends (or in this case, residual income) will grow at a constant rate forever. The formula for the perpetual growth model is shown below:
PT = (RIT+1) / (re - g)
where:
- RIT+1 = expected residual income in the first year after the explicit forecast period (T + 1)
- re = cost of equity
- g = perpetual growth rate of residual income
For our Super Micro Computer example, let's assume a perpetual growth rate (g) of 3%. When selecting an appropriate growth rate, investors should remember the following (as discussed prior):
- Terminal Growth Below GDP Growth: The terminal growth rate should be below the nominal GDP growth rate of the country where the company operates, which is ~5.5% in the U.S. (at the time of writing), as a company cannot outpace the economy indefinitely.
- Terminal Growth Below Cost of Equity: The growth rate should also be below the cost of equity (re), which we calculated to be 11.28% using the CAPM from Step #3. This is because a company's growth rate cannot sustainably exceed the rate of return required by its shareholders.
To calculate "PT," we first need to calculate the residual income for the terminal period (RIT+1). This is done by growing the residual income from the final year of the explicit forecast period (FY 2028) by the perpetual growth rate (g).
First, calculate the residual income for FY 2028 (if you haven't already):
RI2028 = EPS2028 - (re × BVPS2027)
RI [SMCI; FY 2028] = $53.59 - (11.28% × $177.19) --> $33.60
Now, calculate "RIT+1":
RIT+1 = RI2028 × (1 + g)
RIT+1 [SMCI] = $33.60 × (1 + 3%) --> $34.61
Next, calculate "PT":
PT = RIT+1 / (re - g)
PT = $34.61 / (11.28% - 3%) --> $417.91
Then, calculate the expected BVPS at terminal time T (BVPST):
BVPST = BVPS2028 = BVPS2027 + EPS2028 - DPS2028
BVPST [SMCI] = $177.18 + $53.59 - $0 --> $230.77
Finally, calculate "PT - BVPST":
PT - BVPST [SMCI] = $417.91 - $230.77 --> $187.14
The difference between the expected per-share price at the terminal time T (PT) and the expected BVPS at the terminal time T (BVT) is $187.14. This value will be used in the next step, Step #9, to calculate the present value of the terminal value and the intrinsic value of the company.
Step #9: Calculate the Present Value of Residual Income
To determine the present value (PV) of the company's future residual incomes, we need to discount each year's residual income back to the present using the cost of equity as the discount rate. This is done by calculating the discount factor for each year and then dividing the respective year's residual income by the discount factor.
The formula for calculating the discount factor is shown below:
Discount Factor = (1 + re)t
where:
- re = cost of equity (from Step #3)
- t = number of years from the present
For our Super Micro Computer example, let's calculate the discount factor for FY 2024:
Discount Factor [SMCI; FY 2024] = (1 + 11.28%)1 --> 1.1128
Now, to calculate the present value of the residual income for each year, divide the respective year's residual income by the discount factor:
PV of Residual Income = Residual Income / Discount Factor
Here's the output for FY 2024:
PV of Residual Income [SMCI; FY 2024] = $18.40 / 1.1128 --> $16.54
This means that the $18.40 of residual income generated by Super Micro Computer in FY 2024 is worth $16.54 in today's dollars, considering the time value of money and the riskiness of the company's future residual income.
Repeat this process for every year of the explicit forecast period, including the terminal value. For the terminal value year, use the discount factor for the final year of the explicit forecast period (year 5 in our example).
For reference, here's what our two-stage RIM financial model looks like for Super Micro Computer after completing these 9 steps:

By discounting each year's residual income and the terminal value back to the present, we account for the time value of money and the riskiness of the company's future residual income. The sum of these present values will be used in the final step to calculate the company's intrinsic value per share.
Step #10: Calculate and Interpret the Two-Stage Residual Income Model (RIM)
The final step in the two-stage RIM is to calculate the intrinsic/fair value per share of Super Micro Computer by adding the current book value per share (BVPS0) to the sum of the present values of the residual incomes, including the terminal value, as demonstrated below:
Intrinsic Value Per Share = BVPS0 + PV of Residual Incomes + PV of Terminal Residual Value
Intrinsic Value Per Share [SMCI] = $35.24 + ($16.54 + $20.96 + $22.03 + $20.78 + $19.69) + $109.66 --> $244.89
The intrinsic value per share of $244.89 represents the fair value of Super Micro Computer's stock based on the two-stage RIM, taking into account the company's current book value, expected future residual incomes, and the terminal value.
Now, investors should apply a margin of safety to their intrinsic value estimates to account for potential errors in assumptions and to provide a buffer against unforeseen risks.
For instance, if we apply a 15% margin of safety to Super Micro Computer's intrinsic value per share of $244.89, the adjusted intrinsic value or buy price would be:
Buy Price = Intrinsic Value Per Share × (1 - Margin of Safety)
Buy Price [SMCI] = $244.89 × (1 - 15%) --> $208.16
Finally, the stock's valuation can be interpreted like any other intrinsic value calculation:
- Undervalued: Buy Price > Market Price
- Fairly Valued: Buy Price = Market Price
- Overvalued: Buy Price < Market Price
In the case of Super Micro Computer, the current stock price of ~$767.61 (at the time of writing) is significantly higher than the buy of $208.16, suggesting that the stock may be overvalued based on the two-stage RIM.
This overvaluation could be due to various factors, such as underestimating the company's future prospects, bullish market sentiment, or limitations of the RIM itself. Regardless, our valuation suggests that investors should be cautious about investing in Super Micro Computer, as there may be a higher risk of a price correction in the future.
For reference, here's Step #10 completed in our two-stage RIM financial model for Super Micro Computer:

Limitations of Residual Income Valuation
While the residual income model (RIM) offers several advantages, such as focusing on economic profitability and being suitable for companies with irregular dividend patterns and/or negative free cash flows, it also has some important limitations that investors should be aware of when applying the model, as discussed below:
- Dependence on Accounting Data: The RIM relies heavily on accounting information, which can be subject to distortions, manipulations, and differences in accounting policies across companies. This can lead to inconsistencies and inaccuracies in the valuation. For example, earnings per share (EPS) and book value per share (BVPS) can be impacted by non-recurring items, changes in accounting standards, or management's discretionary choices, affecting the reliability of the RIM's inputs.
- Assumption of Positive Net Income: The RIM may not be appropriate for companies with negative net income, as the model assumes that a company will eventually generate positive residual income. If a company is expected to have prolonged periods of negative net income, the RIM may not provide a reliable valuation estimate.
- Lack of Cash Flow Focus: Because the RIM is suitable for companies with negative and/or unpredictable cash flows, it primarily focuses on accounting-based metrics, such as net income and book value, rather than cash flows. Cash flows are often considered to be more accurate and reliable indicators of a company's financial health and performance.
- Sensitivity to Assumptions: The intrinsic value estimate derived from the RIM is highly sensitive to the assumptions used, particularly the cost of equity and the forecasted EPS and DPS figures. Small changes in these inputs can significantly impact the final valuation, making it crucial for investors to use reasonable and well-supported assumptions.
- Reliance on Forecasts: Similarly, the accuracy of the RIM depends on the quality of the residual income forecasts. Forecasting a company's future performance is inherently challenging and prone to errors and biases, as it involves predicting earnings, book values, and other financial variables several years into the future.
- Limited Applicability for Certain Industries: The RIM may not provide meaningful results for companies in cyclical industries, those undergoing significant restructuring, or those with highly volatile earnings. In such cases, other valuation methods may be more appropriate.
- Potential Overvaluation of Capital-Intensive Companies: The RIM may overvalue companies with a large asset base, as the book value is a significant component of the intrinsic value formula. Even if a company's residual income is zero, it will still be valued at its book value, which can be substantial for capital-intensive firms. This may not accurately reflect the company's true economic performance.
- Exclusion of Non-Operating Assets: Like many other valuation models, the RIM does not explicitly account for the value of non-operating assets, such as excess cash or investments in other companies. While this is a limitation, it's not unique to the RIM, and investors may need to make separate adjustments to the valuation to incorporate the value of these assets.
In conclusion, while the RIM can be a valuable tool for estimating a company's intrinsic value, investors should be aware of its limitations. It's recommended to use the RIM alongside other valuation approaches, such as comparable company analysis (comps), and to thoroughly understand the company's fundamentals while using reasonable assumptions. This will help investors make more informed decisions and mitigate the risks associated with relying on a single valuation model.
The Bottom Line
The residual income model (RIM) and its variant, the economic value added (EVA) model, are effective methods for estimating a company's intrinsic value by focusing on economic profitability. While RIM considers the excess earnings generated after accounting for the cost of equity capital, EVA takes a broader view by considering the cost of all capital, including debt and preferred stock. Both models are particularly useful for valuing companies with irregular dividend patterns and/or negative free cash flows expected to turn positive.
The RIM has three main approaches: the standard model, which calculates the present value of each year's residual income separately; the perpetual growth model, which assumes a constant growth rate; and the two-stage model, which combines a detailed forecast period with a terminal value calculation. These models also share similarities with the dividend discount model (DDM), due to the clean surplus relationship between earnings, dividends, and book value.
Despite its advantages, the RIM has several limitations. It relies heavily on accounting data, which can be subject to distortions and manipulations. The model is sensitive to assumptions about the cost of equity and growth rates, and its accuracy depends on the quality of the residual income forecasts. Additionally, the RIM may not be suitable for unprofitable companies or those in cyclical industries with highly volatile earnings, and it may overvalue capital-intensive companies.
In summary, the RIM and EVA models are useful methods for estimating intrinsic value by focusing on economic profitability. However, they should be used alongside other valuation methods, such as comparable company analysis (comps), and with a thorough understanding of the company's fundamentals. This balanced approach will help investors make more informed and accurate investment decisions.
