

In The General Theory of Portfolio Construction (2024), Charles Gave presents an investment framework he developed in 1978 after watching Nixon break the gold standard and financial markets descend into chaos.
Gave, co-founder of the macro research firm Gavekal, started covering markets at a French bank in January 1971.
Seven months later, in August 1971, President Nixon stopped letting foreign governments exchange U.S. dollars for gold. U.S. stocks had peaked in November 1968, and by the time they bottomed in 1982, they’d lost two thirds of their value after inflation. Gave says his goal ever since has been to capture as much upside as he can without getting caught in a bear market that bad again.
He has refined his four quadrants model through five decades of market cycles, offering an approach to asset allocation that depends on just two variables: (1) economic activity and (2) price trends.
Gave observed that economies cycle through four distinct environments, and each environment favors different assets. Get the environment right, and you know what to own. Get it wrong, and you’ll struggle with generating outsized returns.
In 2022, counting dividends and interest, the S&P 500 lost 18%, and the Bloomberg U.S. Aggregate, the main U.S. bond index, lost 13%, its worst year since it began in 1976. Over the same year, the S&P 500 energy sector ETF (XLE) returned 64%:
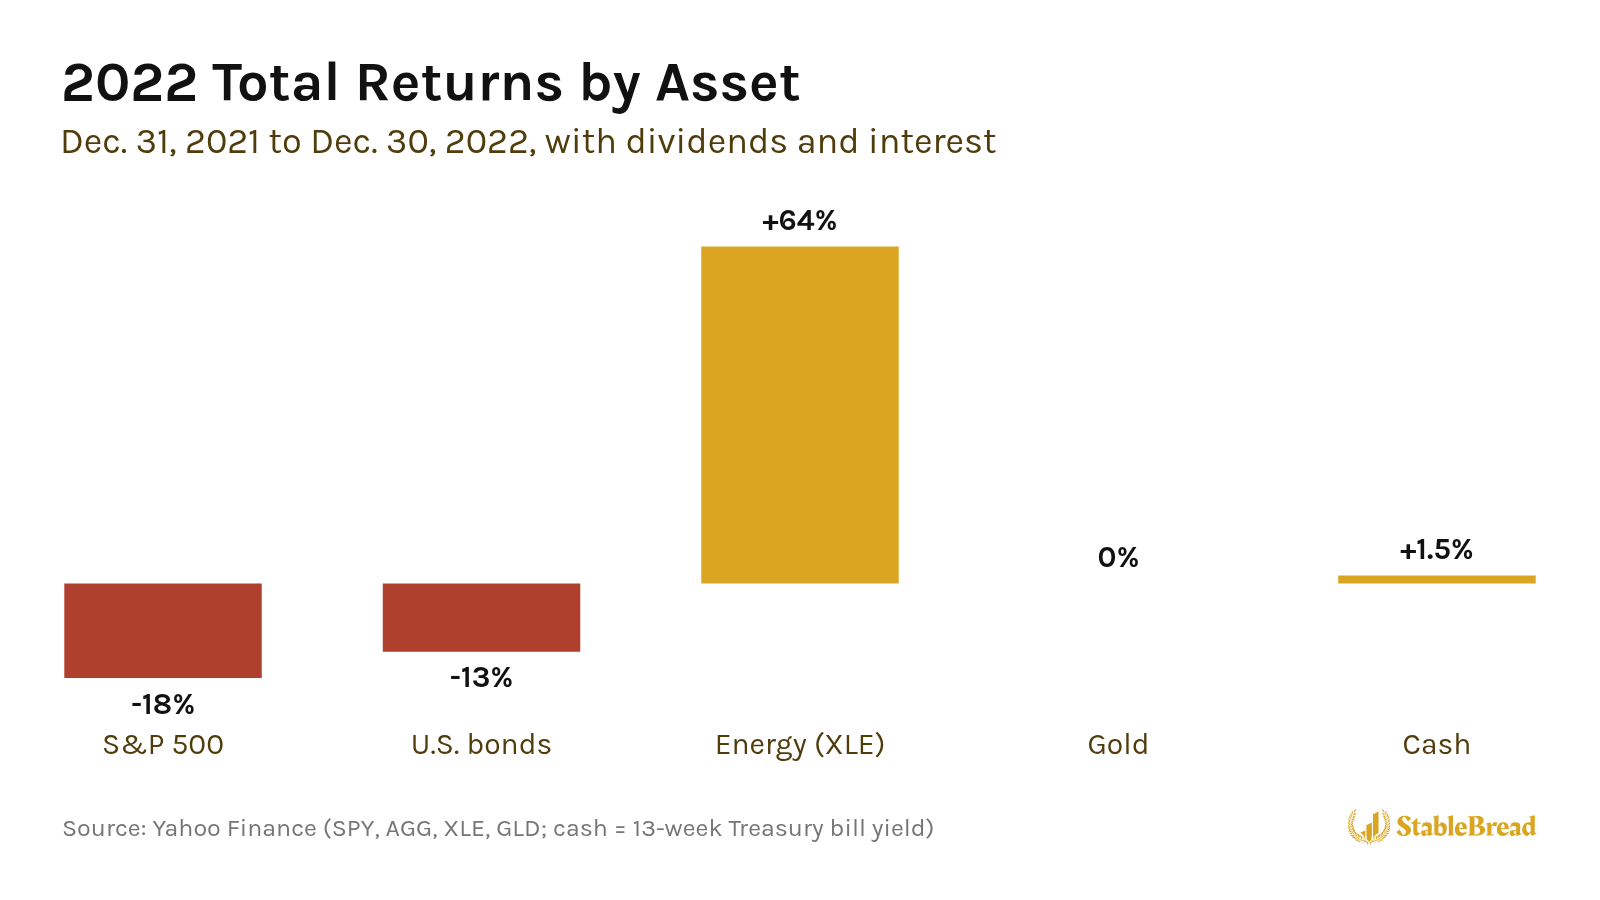
Gave’s framework would’ve said to own cash and energy in 2022, not stocks and bonds. And in my backtest of his rules from January 1970 to September 2026, a portfolio split equally between cash, the S&P 500, and either 10-year Treasuries or gold, whichever the framework favored, returned 5.7%/year after inflation, with a max drawdown of 28% vs. 54% for the S&P 500.
Below, I’ll walk through the four quadrants, the two ratios that show which quadrant the economy is in, how Gave builds a portfolio from the four quadrants, and where the U.S. stands as of September 30, 2026.
Four Quadrants Framework
Gave first published the four quadrants in 1978. The visual below describes that original version of the framework:

The horizontal axis measures economic activity, whether businesses are expanding or contracting.
The vertical axis tracks prices, whether the economy is experiencing inflation or deflation.
This creates four quadrants, each representing a distinct economic environment with a different set of assets Gave favors.
Deflationary Boom (Bottom Right)
Gave defines deflationary boom as “the natural state of capitalism” where entrepreneurs figure out how to produce more goods and services using fewer resources, whether through technology, better processes, or innovation.
This efficiency means production volumes rise while prices fall, with businesses passing savings to consumers.
In this environment, innovative companies with pricing power thrive because they can maintain margins through differentiation, while companies without pricing power struggle as general price levels decline. Growth stocks tend to beat value stocks.
Beyond individual stocks, most long-term investments perform well in this quadrant, including government bonds, corporate bonds, and real estate. Falling prices tend to pull interest rates down, which raises the value of income far in the future.
For context, the late 1990s fit here. From 1995 to 1999, the S&P 500 more than tripled, oil stayed under $30/barrel, and gold fell ~25%.
Inflationary Boom (Top Right)
Wars, massive infrastructure projects, or a rapid rise in government spending as a share of GDP push both prices and economic activity higher.
In this environment, stores of value dominate returns, including gold, commodities, real estate, and high fixed cost cyclical producers. Value managers and emerging market managers also tend to perform well during these periods.
Companies with high fixed costs particularly benefit as inflation reduces their debt burden while revenues rise with prices. In contrast, long-term bonds suffer, since inflation eats away at their fixed payments.
The U.S. has been in this quadrant since November 2023, apart from four weeks in 2026 (see “Where the U.S. Stands Now” below).
Related: How to Protect Your Portfolio Against Inflation
Inflationary Bust (Top Left)
Stagflation represents the investor’s nightmare. Prices rise while the economy contracts. “Very few assets do well,” Gave writes. “Long duration assets do especially poorly.”
Economies often get pushed into stagflation through energy price spikes. When this happens, you should own cash in the safest currency, since even bonds fall hard, and usually energy positions since they’re often driving the inflation. Gold tends to rise too.
Gave also advises selling financial assets because they suffer in stagflation. Earnings collapse, dragging down stock prices, while inflation eats away at bond values.
The 1970s oil shocks created the most famous inflationary bust. In 1973 and 1974, oil prices quadrupled and U.S. inflation hit 12%. The S&P 500 fell 48% from its January 1973 peak to its October 1974 low, while gold nearly tripled over those two years.
Get Our 50-Question Stock Analysis Checklist!
After researching hundreds of stocks, we built this 50-question checklist to guide your analysis and help you avoid costly mistakes.
Download ChecklistDeflationary Bust (Bottom Left)
In a deflationary bust, both prices and sales volumes fall. Companies cannot repay the principal of their debt, bankruptcies surge, and asset prices collapse across the board.
Safe, long-dated government bonds rise as investors flee to safety and interest rates plummet. Cash also tends to gain and gold to hold fairly steady, while stocks fall.
2008 played out that way, measured in total returns:
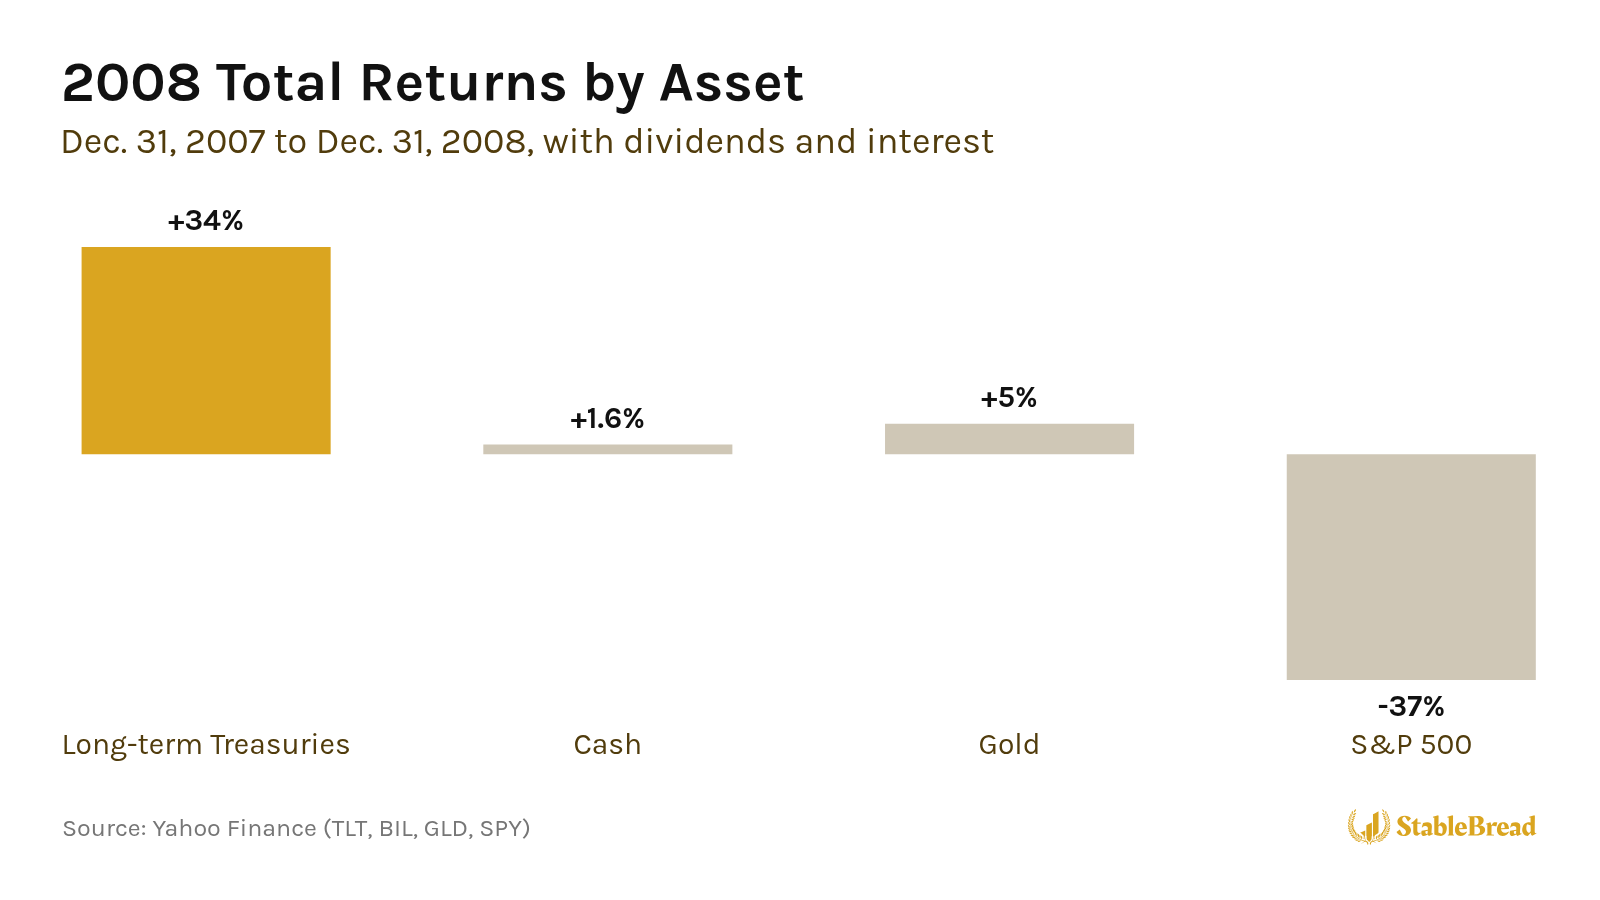
Corporate bonds collapsed alongside equities as credit spreads exploded. Real estate crashed. Commodities plummeted. Gold initially fell before recovering.
Government bonds became the biggest winning trade as the Fed slashed rates to zero and investors sought safety above all else.
So on the left side of the quadrants, the busts, Gave wants to own contracts, meaning bonds and cash, which are promises to pay you back. On the right side, the booms, he wants real assets, meaning stocks, gold, and real estate.
A contract is only as good as the borrower and the currency it’s paid in. So when default or currency debasement becomes a risk, Gave’s answer is gold or other real assets.
Identifying Your Quadrant
Gave spent decades searching for reliable indicators to identify which quadrant the economy occupied.
The problem was that official economic data arrives late and gets revised, while market prices reflect emotion as much as fundamentals.
His solution was to let market prices provide the signals, and he settled on two ratios.
Boom or Bust?
Gave’s first ratio comes from his view that “the economy is nothing but energy transformed.” Energy goes in, and what comes out is worth more than the energy that went in. So economic output depends on how efficiently businesses convert energy inputs into goods and services.
~80% of the energy consumed in the world still comes from fossil fuels such as coal, oil, and natural gas:

In Gave’s view, booms come from cheap energy and busts from expensive energy:
- When businesses extract more value from each unit of energy, the economy expands.
- When energy costs overwhelm the value businesses can create, contraction follows.
For measuring energy costs, Gave looks at the WTI (oil price) in gold terms (WTI/Gold), which provides a proxy of energy costs over time:

Gave notes that most U.S. recessions since 1950 started after oil got more expensive in gold terms.
But to determine which quadrant investors are in, he uses the S&P 500 to WTI ratio (S&P 500/WTI), a proxy measure for energy efficiency.
Since S&P 500 companies represent most of the private sector’s economic activity, their combined value serves as a proxy for what the economy produces. WTI prices represent the cost of energy needed to run factories, transport goods, and power offices.
So when stocks rise faster than oil, companies are turning energy into more value, and Gave expects growth to follow. When oil rises faster, he sees a high chance the economy stalls and stocks do poorly.
Gave tracked this relationship over more than a century to show how the ratio predicts economic expansions and contractions:

Here’s the rule to determine whether you’re on the right or left side of the four quadrants:
- When S&P 500/WTI sits above its seven-year moving average (chart shaded green), you’re on the right side of the quadrants, in either a deflationary or inflationary boom.
- When S&P 500/WTI sits below its seven-year moving average (chart unshaded), you’re on the left side, in either a deflationary or inflationary bust.
The S&P 500/WTI ratio has trended up 1.3%/year over the long run, which Gave attributes to the economy producing more value from each barrel of oil. Strip out that trend, and what’s left closely tracks the Shiller P/E (the CAPE ratio), which divides the S&P 500’s price by its average inflation-adjusted earnings over the last 10 years. So when oil outruns stocks, P/E ratios tend to fall too.
Gave also sees a 28-30 year energy cycle, where ~20 years of cheap, plentiful energy lead to underinvestment, followed by ~10 years of shortages. In a shortage, oil prices can rise even in a recession, as they did in the 1970s, and P/E ratios tend to shrink. That’s why, in a shortage, Gave would rather own energy producers than the companies that use energy.
I created a chart tracking the S&P 500/WTI, as pictured below:
Monthly log scale since 1900. Gray bars: US recessions. Green shading: ratio above 7-year SMA (boom conditions).Inflation or Deflation?
For years, Gave tried to model future inflation using:
- The Phillips Curve, showing the relationship between unemployment and inflation, worked sometimes but failed other times.
- Rising energy prices drove inflation in some periods but had no effect in others.
- Big budget deficits meant higher inflation in certain cases, but not in Japan during the 1990s and 2000s.
So Gave flipped the question. Instead of predicting inflation, he asked whether the bond market was protecting investors against rising prices.
In other words, were long-dated U.S. Treasuries a proper store of value?
To answer this, Gave uses gold as a standard of value and computes the ratio between gold prices and 10-year Treasury total returns, meaning the price change plus the interest (Gold/US10YT):

Here’s how to determine whether you’re in the top or bottom half of the quadrants:
- When Gold/US10YT sits below its seven-year moving average (chart shaded red), bonds are outperforming gold and serving as a proper store of value. This places investors in the bottom two quadrants (deflationary boom or deflationary bust).
- When Gold/US10YT rises above its moving average (chart unshaded), gold is outperforming bonds, signaling currency debasement. This places investors in the upper two quadrants (inflationary boom or inflationary bust).
On Gave’s chart, those stretches lasted as long as two decades, like 1984 to 2004, when bonds were the better store of value.
I also created a chart tracking gold relative to Treasury bonds using IEF (Gold/IEF), the iShares 7-10 Year Treasury ETF:
Monthly log scale since July 2002. Gray bars: US recessions. Red shading: ratio below 7-year SMA (bonds outperforming gold).Since 10-year Treasury total return data is difficult to access for retail investors, IEF serves as a suitable proxy. It captures both bond price changes and interest payments, closely approximating the total return measure Gave uses.
On my version of the chart, gold has been beating bonds since March 2020.
Related: How Gold Works as a Portfolio Hedge
Refining the Axes
Having discovered that these two ratios (S&P 500/WTI and Gold/US10YT) effectively identify quadrant positions, Gave realized the original axes, “economic activity” and “prices,” were too vague.
What the ratios actually measure is far more specific: (1) energy efficiency and (2) currency quality. So, for the first time since establishing the four quadrants in 1978, Gave renamed the axes to reflect these measures:

The horizontal axis now tracks “energy efficiency” vs. “energy inefficiency.” The vertical axis shows “good currency” vs. “bad currency.”
The four investment environments and what to own in each haven’t changed, but now each gets a score based on combining the two ratios:
- Energy efficient with good currency (+1 + 1 = +2): Deflationary boom where capitalism thrives, the best environment for investors.
- Energy inefficient with bad currency (-1 - 1 = -2): Inflationary bust, the worst scenario where very few assets perform well.
- Energy efficient with bad currency (+1 - 1 = 0): Inflationary boom, a mixed environment where gold and stocks rise and bonds fall.
- Energy inefficient with good currency (-1 + 1 = 0): Deflationary bust where making money is very challenging, another mixed environment.
Because these readings come from market prices instead of economic data, they don’t always match the textbook labels.
U.S. GDP grew every year from 2001 to 2007, but over those years oil more than tripled while the S&P 500 rose 11%. In Gave’s chart, S&P 500/WTI stayed below its 7-year average from 2001 to 2013, which kept the U.S. on the bust side.
And 2008 looked like a deflationary bust on paper, since prices fell late that year and the economy shrank. But gold had been beating bonds since 2004, so Gave’s version scores 2008 as an inflationary bust.
S&P 500 to Gold Ratio
Gave also tracks a third ratio, the S&P 500 to gold ratio (S&P 500/Gold), to tell bull markets from bear markets. If stocks are beating gold, it’s a bull market. If gold is beating stocks, it’s a bear market.
His logic is that if stocks can’t beat gold over time, there’s no reason to take the risk of owning businesses.
He calls the bear markets that wreck portfolios the “Ursus magnus” variety (Latin for great bear), meaning a stock market that falls 40% or more after inflation.
By his count, the U.S. has had four big bull markets since 1920 (1921 to 1929, 1941 to 1969, 1980 to 2000, and one that started in 2012 and may have peaked in 2021, because gold has beaten stocks since then). Each of the first three ended in an Ursus magnus. After the 2000 peak, the S&P 500 lost more than half its value after inflation by 2009, and more than 80% measured in gold by 2011.
Gave then lined S&P 500/Gold up against his quadrant scores to see how different economic environments performed over the past century:

The results show a clear pattern:
- True U.S. bull markets, when stocks outperform gold over time, mostly took place in the bottom right quadrant (deflationary boom, +2).
- The Ursus magnus bear markets mostly hit in the upper left quadrant (inflationary bust, -2), like the 1970s and 2008.
- When the economy sits in the upper right (inflationary boom) or lower left quadrants (deflationary bust), nothing too dramatic tends to happen.
Gave also observes that S&P 500/Gold falling below its seven-year moving average has never been a good sign, and that it has often come a few months before the same in S&P 500/WTI. This provides early warning that energy efficiency may soon deteriorate, potentially shifting the economy from boom to bust.
Interestingly, from August 2018 to late 2024, the S&P 500 returned 134% with dividends and gold rose 115%, so measured in gold, the S&P 500 went nowhere. As Gave puts it, both gains mostly reflect the U.S. dollar losing value, which he calls a “monetary illusion”:

After 54 years in markets, Gave concludes that success comes not from predicting the unpredictable but from recognizing which economic environment you’re in and positioning accordingly.
No single strategy works in all environments. However, those who recognize the quadrant shifts and adapt their portfolios can prosper through each cycle.
Note: Gave recommends buying setbacks in the S&P 500 during deflationary booms (bottom right), even those caused by recessions. These dips are opportunities. But sell any rallies during inflationary busts (upper left). Those bounces won’t last.
How Gave Builds a Portfolio
In the last four chapters of The General Theory of Portfolio Construction, Gave turns the four quadrants into a portfolio.
Permanent Portfolio
Gave’s starting point is the Permanent Portfolio from Harry Browne, an investment writer who laid it out in his 1999 book Fail-Safe Investing. Browne’s logic was that no one can reliably forecast the economy, so you split your money equally across four assets that each do well in a different quadrant.
In Gave’s version, that’s 25% each in cash, 10-year Treasuries, the S&P 500, and gold, rebalanced back to 25% from time to time.
I reran Gave’s backtests through September 2026. From January 1970, the Permanent Portfolio returned 4.2%/year after inflation, with a max drawdown of 23%. The S&P 500 returned 6.9%/year after inflation, but with more than twice the volatility and a max drawdown of 54%.
Note: My backtest rebalances monthly and uses data from Robert Shiller, Yahoo Finance, and the World Bank. Gave’s book reports 4.1%/year for the Permanent Portfolio and 6.8%/year for the S&P 500 through 2024.
Gave explains the result with the four quadrants:
- Deflationary boom: Stocks, bonds, and cash rise, and gold underperforms.
- Inflationary boom: Stocks and gold rise, cash does very little, and bonds fall.
- Deflationary bust: Bonds and cash rise, gold stays fairly stable, and stocks fall.
- Inflationary bust: Gold and cash rise, while stocks and bonds fall.
So the Permanent Portfolio goes up in three of the four quadrants, and the inflationary bust is where it takes its losses.
Exclusion Game
Gave then improves on the Permanent Portfolio with what he calls the exclusion game. He says he may not know which quadrant the economy is in, but he has a good idea which quadrants it’s not in.
Bonds are the asset to own in a deflationary bust, and gold is the asset to own in an inflationary boom. They sit in opposite corners of the quadrants, so in his framework, the environment that favors one works against the other.
So instead of holding both, he holds whichever Gold/US10YT favors. When the ratio is below its 7-year average, he owns bonds. When it’s above, he owns gold.
In Gave’s backtest, the rule said to own gold until 1984, bonds until 2004, gold until 2013, bonds until 2020, and gold since April 2020.
That three-asset version, a third each in cash, the S&P 500, and either bonds or gold, returned 5.7%/year after inflation from January 1970 through September 2026 in my backtest (Gave’s book reports 5.5%/year through 2024). The three-asset version’s max drawdown was 28%, and its volatility was ~half the S&P 500’s:
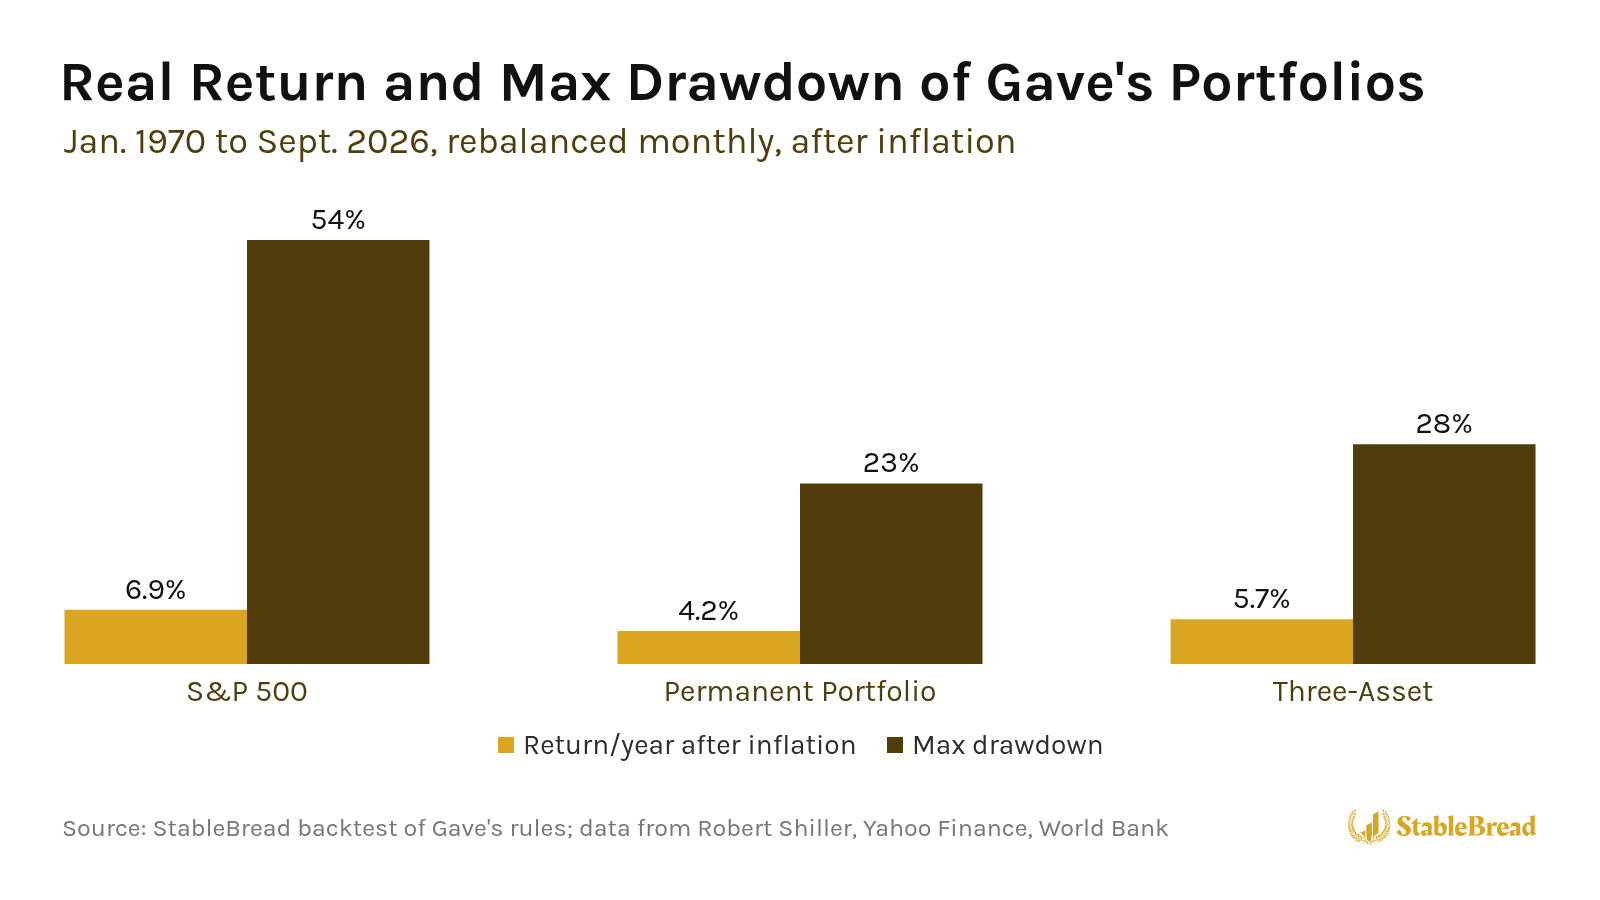
Gave’s benchmark is 4%/year after inflation with fairly low volatility, and the three-asset version’s 5.7% beats that benchmark. It gives up 1.2 percentage points a year vs. the S&P 500 in exchange for about half the drawdown.
Adding Energy
Gave also adds energy, because the Permanent Portfolio still lost a quarter of its value in the 1970s oil shocks. When he wrote the book, energy companies were ~4% of the S&P 500 vs. 30% in 1980, so rebalancing into the S&P 500 buys very little energy.
In his backtest from 1970 to 2024, adding a separate bucket of energy producers lifts the Permanent Portfolio to 5%/year after inflation. Combining that energy bucket with the bonds-or-gold switch gets him to 6.1%/year after inflation, with 10% volatility and a max drawdown of 38%.
Where the U.S. Stands Now
I built Gave’s framework into my free macro dashboard, so you can check the quadrant without rebuilding any of these charts yourself. Its Gave panel uses the renamed axes and plots a dot built from S&P 500/WTI and Gold/IEF. The further the dot is from the center, the further each ratio is from its 7-year average.
Related: How Growth and the Real Fed Funds Rate Signal Recession Risk
The panel runs on market prices, so there’s no waiting on economic reports, and the readings don’t get revised after the fact the way GDP or jobs data does.
When the Quadrant Flipped
The quadrant only changes when a ratio crosses its 7-year average. When a ratio sits near its average, the dot can flip back and forth, as it did nine times between December 2022 and November 2023.
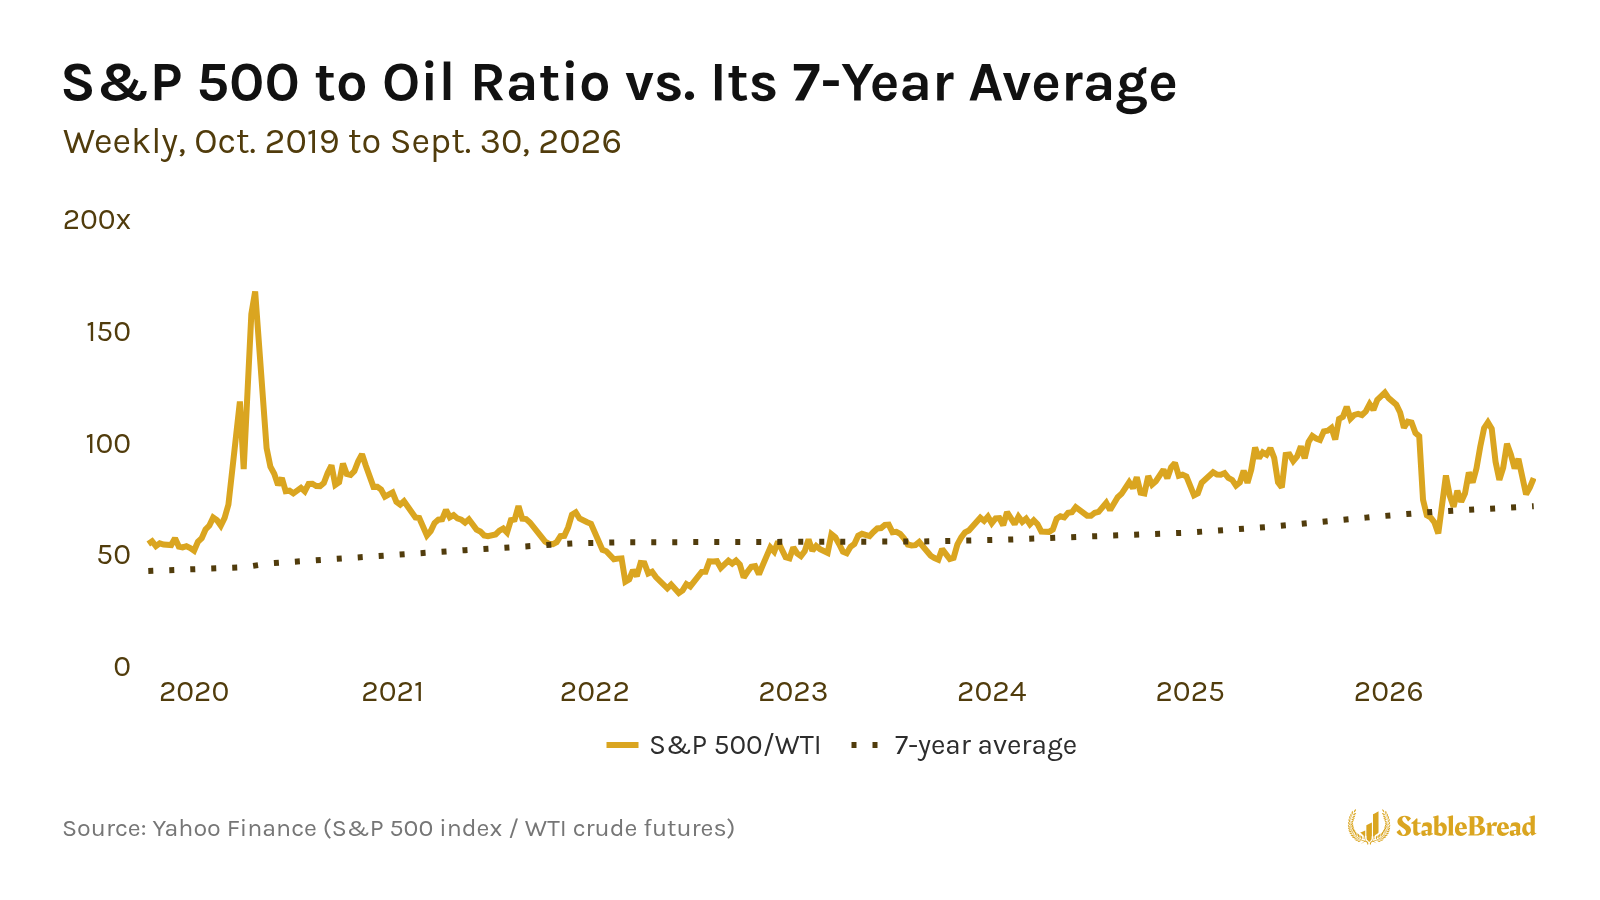
In 2022, oil spiked above $100/barrel, and by June, S&P 500/WTI was in the low to mid 30s, far below its 7-year average of ~55. Gold was beating bonds too, so the panel showed an inflationary bust for 49 of the 52 weeks in 2022, the year cash and energy beat stocks and bonds.
In early 2026, WTI jumped from ~$67 at the end of February to over $110 in early April. The S&P 500 fell ~7% in a month, and the panel showed an inflationary bust for four weeks, then flipped back once oil came down. Both episodes show up on S&P 500/WTI:
Quadrant as of September 30, 2026
As of September 30, 2026, the U.S. is in an inflationary boom, and it’s been there since November 2023, apart from those four weeks in 2026.
S&P 500/WTI ended September at ~85, meaning the S&P 500 index was worth ~85 barrels of oil, above its 7-year average of ~71. So the U.S. is energy efficient.
Gold/IEF ended September at ~47, meaning an ounce of gold bought ~47 shares of IEF, well above its 7-year average of ~26. So gold has been beating bonds by a wide margin, and Gave’s bonds-or-gold rule says to own gold, not bonds.
That scores +1 for energy efficiency and -1 for currency debasement, netting to zero.
For this quadrant, the dashboard’s list says to own gold, commodities, real estate, value stocks, emerging markets, and cyclicals with high fixed costs, and to avoid long-duration bonds. The idea is to own real assets whose prices tend to rise with inflation, and avoid bonds whose fixed payments lose value as prices rise.
What to Watch
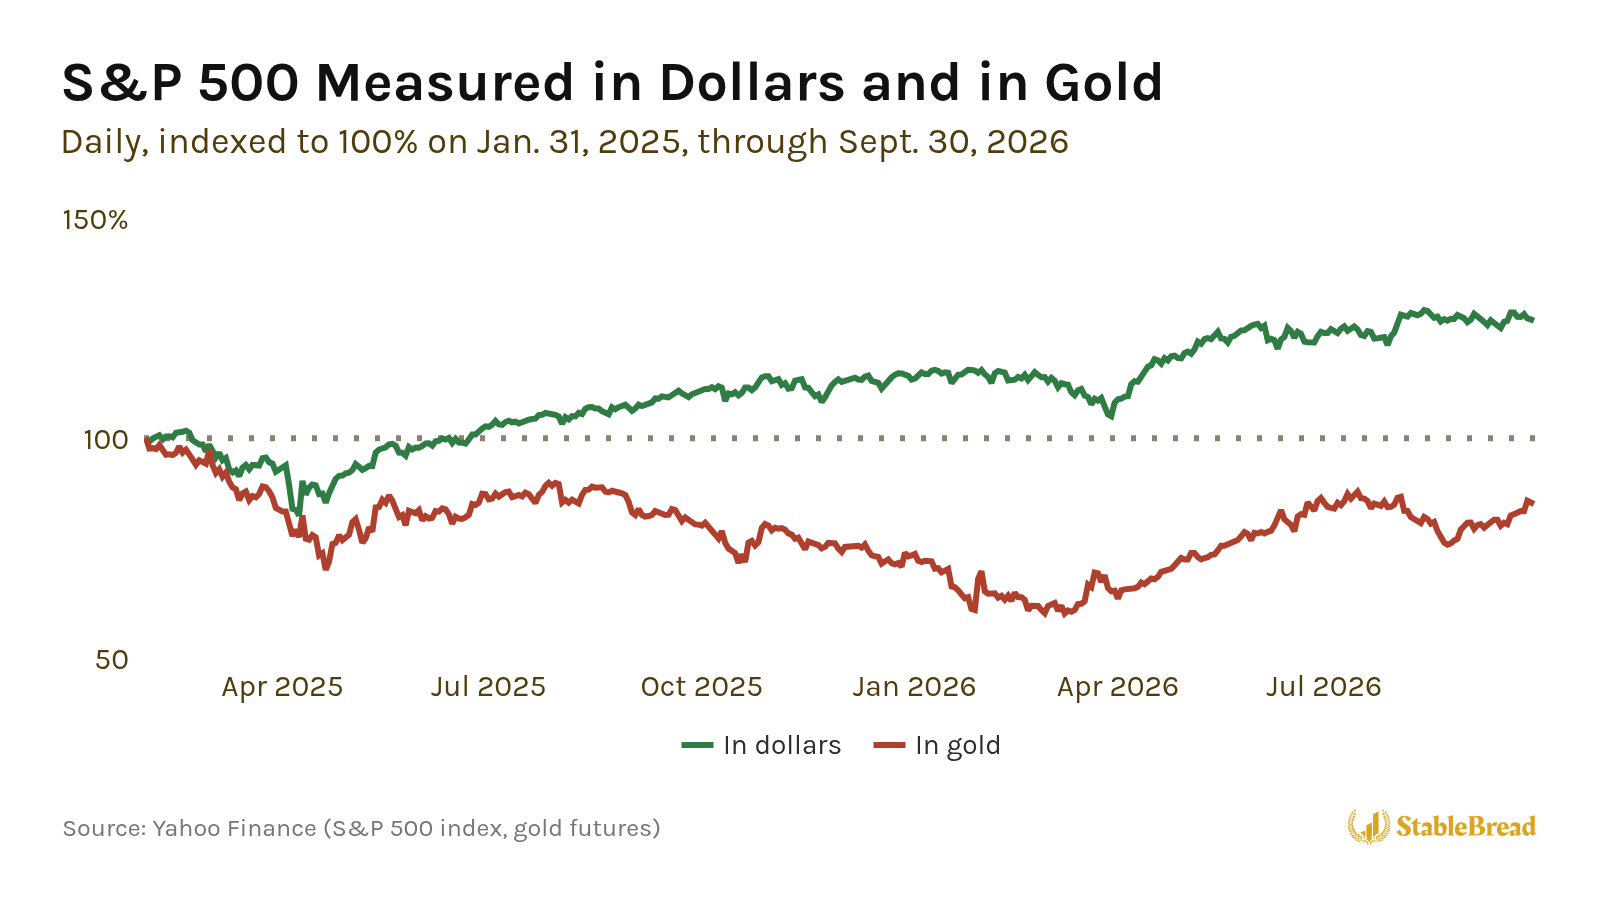
The chart I’m watching most is S&P 500/Gold. S&P 500/Gold ended September at ~1.83, meaning the S&P 500 index was worth ~1.83 ounces of gold, below its 7-year average of ~2.07.
The ratio first broke below its average in October 2024, the same month Gave flagged the break in his book, moved back above after the November 2024 U.S. election, and has stayed below since the end of January 2025.
Gave defines a bear market as stocks falling behind gold, so by his definition, U.S. stocks have been in a bear market since January 2025. From the end of January 2025 to the end of September 2026, the S&P 500 rose ~27% in dollars but fell ~15% measured in gold:
Since January 2025, S&P 500/WTI has dropped below its 7-year average only once, for four weeks in March and early April 2026, when oil spiked. If S&P 500/WTI drops below its 7-year average again and stays there, the U.S. moves to the top-left quadrant, an inflationary bust like 2022.
Bottom Line
Gave’s framework comes down to two ratios built from market prices. S&P 500/WTI tells you whether companies are turning energy into value (boom or bust), and Gold/US10YT tells you whether bonds are holding their value (deflation or inflation).
Together, the two ratios place the economy in one of four quadrants, each with its own assets to own and avoid. And S&P 500/Gold gives an early warning when a boom may be turning into a bust.
While this article covers the framework, how to identify your current quadrant, and the portfolio Gave builds on the framework, read the book for what it doesn’t cover, including why the declining U.S. dollar monopoly means investors should consider gold priced in multiple currencies, not just dollars.
