

In 2021, the S&P 500’s net profit margin was 12.2%. If accounting rules treated what companies spend on research, brands, and software the way they treat a new factory, that margin would have been 13.7%:
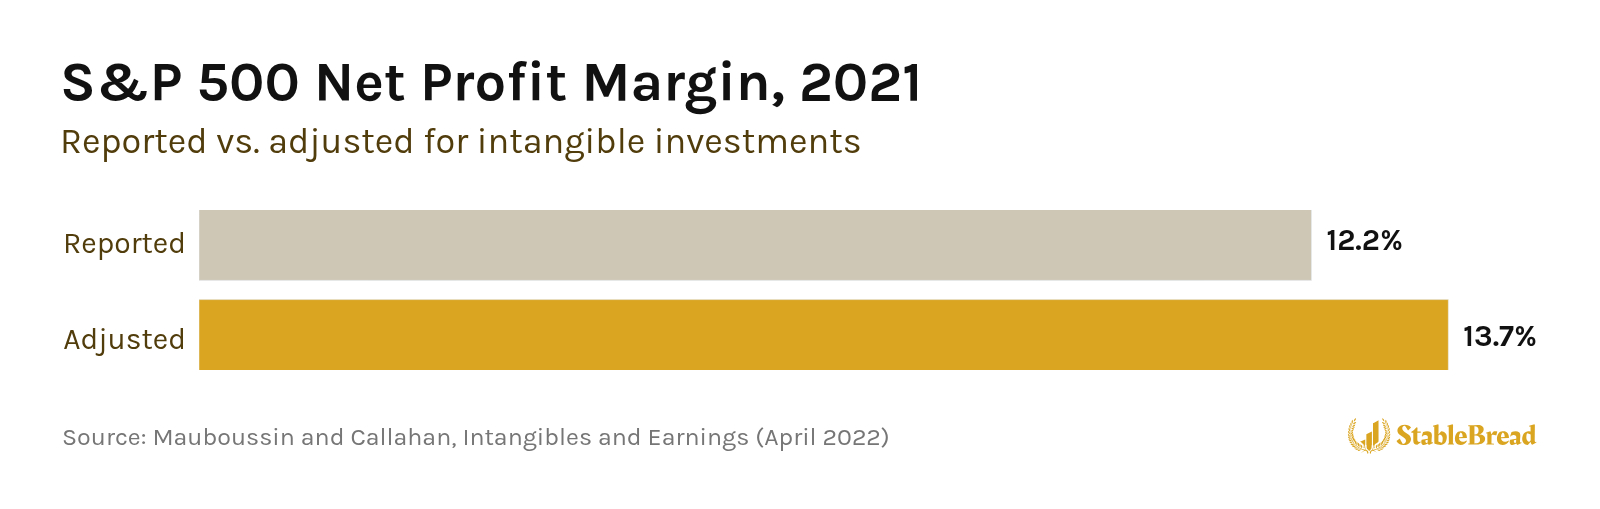
In other words, the companies in the S&P 500 would've reported 11.8% more profit, or ~$170B, according to a 2022 paper titled “Intangibles and Earnings,” by Michael Mauboussin and Dan Callahan of Counterpoint Global, part of Morgan Stanley Investment Management.
That’s because accounting rules record a factory as an asset and spread its cost over the years it’s used, while spending on intangibles like research, brands, and software is mostly recorded as an expense right away, in the year it’s spent.
So accounting rules treat physical and intangible investments differently, despite their similar economic purpose.
Mauboussin and Callahan’s solution is to capitalize (i.e., record as assets rather than expenses) intangible investments and amortize them over their useful lives, treating them exactly like physical investments.
For Palantir Technologies (PLTR), the data analytics software company, the same kind of adjustment lowers its P/E ratio from 113x to 98x, based on its results for the 12 months through September 30, 2026.
So if you value companies on their earnings, especially companies that invest heavily in intangible assets, like tech companies, you need to know how much of their expenses are actually investments, and how to adjust their results for those investments.
Below, I’ll explain why accounting treats these two kinds of investment differently, how that distorts the valuation ratios most investors use, and how to capitalize intangible investments step by step, using Palantir’s latest results.
The Accounting Problem
Financial statements are supposed to give investors the information they need to make investment decisions about a company. But a major shift from physical to non-physical investments has made these statements less useful than they once were.
There are two types of investments companies make to grow their business:
- Tangible investments: Physical assets like factories, machinery, equipment, and vehicles.
- Intangible investments: Non-physical assets like research, brand development, software, and customer relationships.
In the U.S., investment in intangible assets passed investment in tangible assets in the 1990s, as Mauboussin showed in an April 2025 talk at the Ben Graham Centre’s Value Investing Conference.
By 2023, intangible investment came to ~16.5% of GDP, vs. ~10% for tangible investment, per the Global INTAN-Invest database.
The problem, as Mauboussin and Callahan observed, is that U.S. accounting rules (GAAP) treat these two types of investments very differently:
Tangible investments:
- Recorded on the balance sheet as assets.
- Depreciated over their useful lives.
- Depreciation shows up as an expense on the income statement.
Intangible investments:
- Immediately recorded as an expense on the income statement.
- Only appear on the balance sheet if acquired (i.e., not created internally by the company itself).
- Not systematically amortized unless acquired.
There are a few exceptions, like some software development costs. And most acquired intangibles are amortized, which is the intangible version of depreciation, over their useful lives.
So intangible investments don’t appear on the balance sheet like physical assets do, making financial statements less accurate in representing a company’s true value.
How Accounting Distorts Company Value
Here’s an example from Mauboussin and Callahan’s paper to illustrate why this matters:
- Company A buys a $1,000 machine expected to last 5 years and generate $1,500 in value.
- Company B spends $1,000 to acquire a customer expected to remain for 5 years and generate $1,500 in value.
Though these investments are identical in economic terms, their accounting treatment differs dramatically:
- Company A records the machine as an asset and depreciates $200 annually for 5 years (straight-line depreciation).
- Company B immediately expenses the entire $1,000 as a selling cost.
As a result, in the first year, Company B reports $800 less profit than Company A, even though both companies made the same investment:
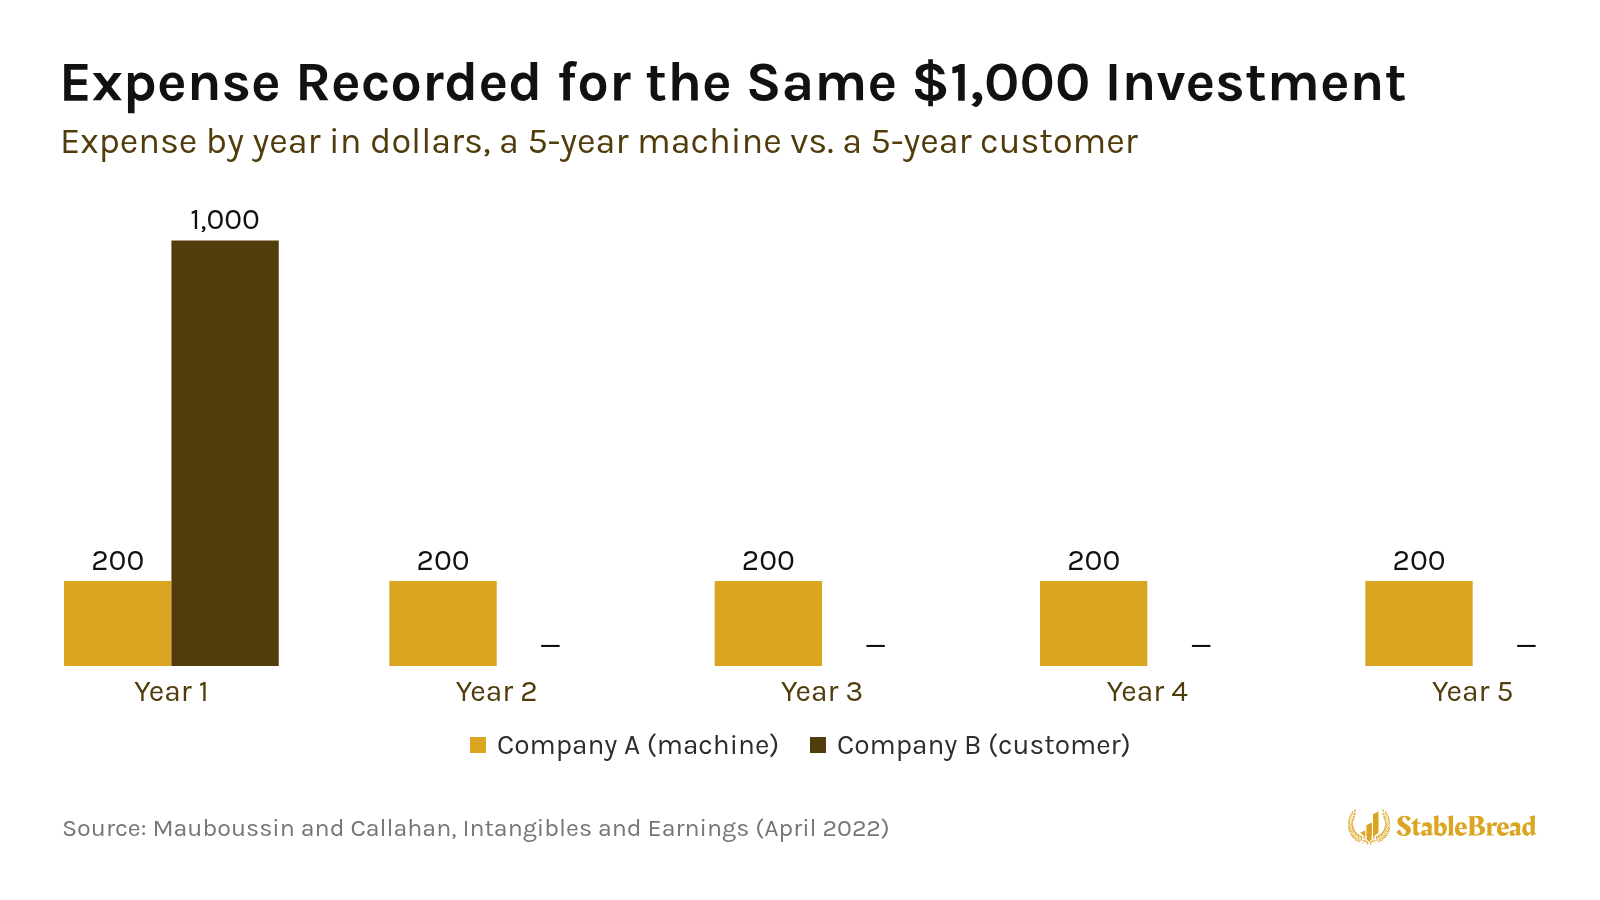
Company B’s reported profits also fall further the faster it grows, since it spends more to win new customers, even though winning those customers creates value.
In a 2023 study, accounting researchers Feng Gu, Baruch Lev, and Chenqi Zhu compared companies whose losses came only from expensing their intangible investments, which they call accounting-driven losses, with profitable companies and with companies whose losses were real.
Here’s what $1 invested in each group in 1980 grew to by 2017:
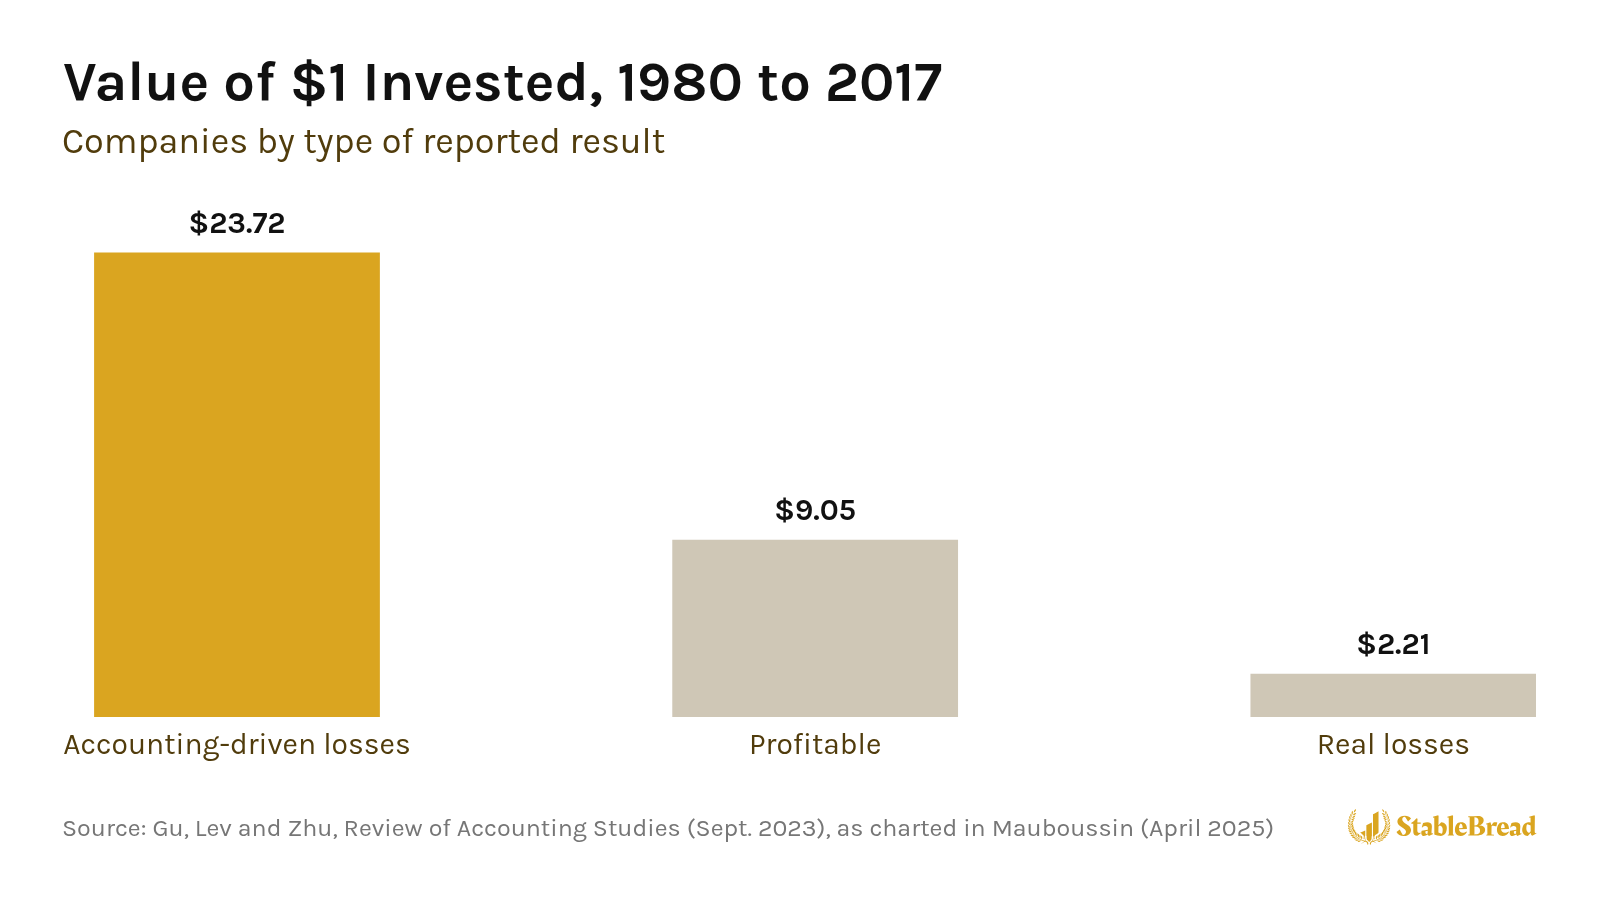
The companies with accounting-driven losses turned $1 into $23.72, vs. $9.05 for the profitable companies and $2.21 for the companies with real losses. So a loss that comes from expensing intangible investments isn’t the same as a real loss.
Related: Why Earnings Per Share (EPS) is Flawed in Stock Analysis
Valuation Distortions From Intangible Accounting
To understand how expensing intangibles affects valuations, Mauboussin and Callahan separate a company’s financial results into what they call two piles.
One pile is its earnings, from the income statement, and the other is its investments, recorded on the balance sheet.
A discounted cash flow model takes both piles into account. Ratios like P/E rely on earnings alone, while P/B relies on the investments. So this accounting inconsistency affects each of the three main valuation approaches differently.
Discounted Cash Flow
When investors use a discounted cash flow (DCF) model, they estimate the total cash a company will generate minus what it spends on investments.
In theory, DCF calculations remain unchanged because they consider both earnings and investments. Whether you expense or capitalize an investment, free cash flow (FCF) stays the same:
- As reported: The company’s operations generate $250 of cash and it invests $100, leaving $150 of FCF ($250 - $100).
- Adjusted: Moving $100 of operating expenses that were actually investments raises its operating cash flow to $350 and its investments to $200, still leaving $150 of FCF ($350 - $200).
Despite the FCF remaining the same, separating earnings from investments correctly tells you how much the company actually invests, which helps you estimate how fast it can grow.
Capitalizing can also change your DCF’s terminal value, which is the value of all the cash flows beyond the final year of your forecast. Many DCFs calculate it as a multiple of the final year’s earnings, so if those earnings are adjusted up, the terminal value goes up as well.
Earnings Multiples
Popular valuation ratios like P/E and EV/EBITDA can be significantly distorted by how intangibles are treated.
In their paper, Mauboussin and Callahan analyze Amazon (AMZN) as an example. For 2021:
- Amazon’s reported net income was $33.4B.
- After reclassifying $60.1B of expenses as investments and subtracting the amortization of what Amazon had invested in earlier years, net income increases to ~$61B.
Capitalizing those expenses would've nearly doubled Amazon’s earnings, making its P/E ratio ~45% lower.
Amazon’s EBITDA would have effectively doubled, since amortization isn’t subtracted from EBITDA, so EBITDA rises by the full amount capitalized.
So comparing multiples from one company to the next, without breaking down how much of each one’s expenses are actually investments, can lead you to the wrong conclusion.
Related: How Share-Based Compensation Distorts Earnings and How to Adjust for It
Book Value Ratios
The P/B ratio compares a company’s market value to its accounting book value.
Book value, also known as shareholders’ equity, represents a company’s assets minus its liabilities, essentially what shareholders would theoretically receive if the company were liquidated.
P/B Ratio = Current Stock Price / Book Value Per Share
The P/B ratio is directly affected by how you account for intangibles.
When intangible investments are immediately expensed, they never appear as assets on the balance sheet. That makes book value artificially low, since these valuable investments aren’t counted as assets despite creating real economic value.
So for companies that invest heavily in intangibles, P/B ratios look higher than they should.
That’s a problem for investors who look for cheap stocks using P/B ratios. In the early 1990s, finance professors Eugene Fama and Kenneth French showed that stocks with low P/B ratios had earned higher returns than stocks with high ones. That gap in returns is called the value premium.
However, in a 2021 paper, “The Value Premium,” Fama and French found that value premiums were much lower, on average, from 1991 to 2019 than from 1963 to 1991.
Get Our 50-Question Stock Analysis Checklist!
After researching hundreds of stocks, we built this 50-question checklist to guide your analysis and help you avoid costly mistakes.
Download ChecklistMauboussin and Callahan argue that’s what you’d expect if more and more of what companies invest is missing from book value.
Several studies they cite also found that the value factor works better when book value includes intangible investments, because the adjusted book values more accurately reflect each company’s true investment base.
Capitalizing Intangible Investments
Mauboussin and Callahan’s solution is to treat intangible investments the same way accounting treats tangible ones.
In other words:
- Identify which expenses on the income statement are actually investments.
- Move these investments to the balance sheet (capitalize them).
- Amortize them over their useful lives.
However, this raises two key questions:
- Which expenses should be considered investments?
- What’s the appropriate useful life for these assets?
Researchers have answered both questions in three ways, from one rule for every company to estimates by industry.
Identifying Investment Expenses
Approach #1: Standard Academic Method
According to Mauboussin and Callahan, academics who study intangible investments often count 100% of R&D plus 30% of non-R&D SG&A as investments, and assume the same useful life for every company.
Mauboussin and Callahan call that “a step in the right direction” but “a blunt tool,” since the investment component of SG&A varies widely by industry and company.
So this approach is too general for accurate company-specific analysis.
Approach #2: Maintenance vs. Growth SG&A
Mauboussin and Callahan highlight research by accounting professors Luminita Enache and Anup Srivastava (2018) that separates SG&A expenses into:
- Maintenance SG&A: Expenses needed to sustain current operations.
- Investment SG&A: Expenses that pursue growth and create future value.
This framework establishes the conceptual foundation for identifying investment expenses within SG&A, but doesn’t provide specific parameters for implementation across diverse industries.
Approach #3: Industry-Specific Analysis
Further research by Iqbal, Rajgopal, Srivastava, and Zhao (2022), in a working paper, analyzed 42 industries to determine:
- What percentage of SG&A expense is an investment?
- What is an appropriate asset life?
Iqbal et al. separated SG&A into two components: Main SG&A (all SG&A expenses excluding R&D) and R&D expense.
Iqbal et al.’s findings show significant variation across industries:
- The investment portion of Main SG&A (excluding R&D) ranges from 0% to 80%, with an average of 54%.
- The investment portion of R&D ranges from 7% to 98%, with an average of 76%.
- Useful lives for Main SG&A investments range from 0.25 to 5 years (average 3.3 years).
- Useful lives for R&D investments range from 0.5 to 7 years (average 4.4 years).
These wide ranges show that a one-size-fits-all approach to capitalizing intangibles won’t work across different industries.
So instead of one rule for every company, it’s better to use the percentages and useful lives of the company’s own industry when adjusting its financial statements.
Note: These figures are from the February 2022 version of the working paper, which Mauboussin and Callahan’s paper reproduces. The study was published in Management Science in 2025 as “A Better Estimate of Internally Generated Intangible Capital,” with estimates by industry and year.
Growth’s Impact on Adjustments
Beyond identifying what portion to capitalize, the difference between reported and adjusted earnings also depends on the growth rate of investment SG&A.
When a company’s investment spending grows, the amount removed from current expenses exceeds the amortization added back from past investments.
For example, consider a company with $1,000 in SG&A where 30% is considered an intangible investment with a 3-year life:
- If SG&A doesn’t grow, eventually you’ll be capitalizing $300 and amortizing $300 ($100 from each of the last three years), with no net effect.
- If SG&A grows at 10% annually, you’ll have a 5.1% net reduction in SG&A expense, increasing profits.
Here’s the math behind the 5.1% ($68 / $1,331), with amortization beginning the year after each investment:
In year 1, the company capitalizes $300 and amortizes nothing yet, so its expenses fall by the full $300. By year 4, SG&A is $1,331, and the company capitalizes $399 and amortizes $331, a third of each of the previous three years’ investments. That leaves a net $68, so its SG&A expense is 5.1% lower and its profit is $68 higher.
So the faster a company’s investment spending grows, the further its reported profits fall below its adjusted profits, since what it spends today keeps outpacing the amortization of what it spent before.
Moreover, reclassifying expenses as an investment also boosts book value, since assets increase and shareholders’ equity rises while liabilities stay the same. According to Iqbal et al., these adjustments can increase book value by 4-95% across industries (49% average increase).
S&P 500 Estimate
Mauboussin and Callahan estimated the S&P 500’s adjusted profits for 2021 by assuming that 60% of the companies’ SG&A was an investment, with a 4-year useful life, growing 6% per year.
That adjustment raised the S&P 500’s net income by 11.8%, ~$170B, and its net profit margin from 12.2% to 13.7%.
Hulten’s Split and Microsoft’s ROIC
Mauboussin has kept working on intangibles since the 2022 paper. In his April 2025 talk, he adjusted Microsoft’s (MSFT) results using a split by expense line from economist Charles Hulten’s 2010 study, “Decoding Microsoft.”
Hulten chose his percentages for a tech company like Microsoft, adjusting the guidance of earlier research on the whole economy. His split counts these shares of each expense line as investments:
- R&D (100%): Aimed at future products.
- Sales and marketing (70%): In Hulten’s words, a product “has no economic value unless people know about it and want to buy it.”
- General and administrative (20%): Mostly the day-to-day running of the company, like payroll and accounting, with only a small part going to longer-term work like strategic planning.
Using that split, $48.2B of the $57.5B Microsoft spent on R&D, sales and marketing, and G&A in its fiscal 2024 (ended June 30, 2024) was an investment.
Capitalizing those investments raised Microsoft’s after-tax operating profit from $97B to $108B. However, the adjustment also raised the capital Microsoft had invested, from $253B to $353B on average. So Microsoft’s return on invested capital (ROIC) fell from 38% to 30%, calculated as:
ROIC = NOPAT / Invested Capital
where:
- NOPAT = after-tax operating profit (net operating profit after taxes)
- Invested Capital = average of the capital invested at the fiscal year’s start and end
With intangibles capitalized, Microsoft’s ROIC is 30% ($108B / $353B) instead of 38% ($97B / $253B), since the adjustment raises invested capital by more, proportionally, than it raises NOPAT.
In a November 2022 follow-up, “ROIC and Intangible Assets,” Mauboussin and Callahan adjusted the ROIC of the non-financial companies in the Russell 3000, an index of ~3,000 U.S. companies, using Iqbal et al.’s industry estimates.
Mauboussin and Callahan found that the adjustment lowers the ROIC of companies with high returns and raises it for companies with low ones. In their words, capitalizing intangible investments “makes the highs lower and the lows higher.”
Adjusting Palantir’s Financial Statements for Intangibles
I’ll use Palantir as a real-world example, based on its results for the 12 months through September 30, 2026, the latest it had reported as of November 11, 2026.
Palantir describes its business in its 10-K for 2025 by saying, “We build software that empowers organizations to effectively integrate their data, decisions, and operations at scale.” Palantir sells that software to government agencies and to companies.
Unlike manufacturers with physical equipment, Palantir’s value comes mostly from intangible assets like software and customer relationships. Most of what Palantir spends to build its software and win customers is recorded as an expense, in its sales and marketing, R&D, and G&A lines, which may hide its true profitability.
Over the 12 months through September 30, 2026, those three lines added up to $2.85B, against $7.29B of revenue, per Palantir’s 10-Q for the quarter ended September 30, 2026 and its 10-K for 2025.
Step #1: Estimate Investment Portions
Iqbal et al. group companies by their SIC codes (standard industry codes), and Palantir’s code, 7372 for prepackaged software, falls under business services. Based on Appendix A from Iqbal et al. (page 8 of Mauboussin and Callahan’s paper), the business services industry means:
- 54% of Main SG&A should be treated as investment with a useful life of 4.4 years.
- 62% of R&D should be treated as investment with a useful life of 6.7 years.
Palantir’s SG&A, its sales and marketing plus its G&A, is about three times its R&D. So weighting the two that way, I capitalized 56% of Palantir’s combined SG&A and R&D, with a useful life of 5 years.
Note: You could develop multiple scenarios by varying both the capitalization percentage and/or useful life to establish a range of possible net adjustment figures rather than a single point estimate. I test one alternative, Hulten’s split, at the end of this section.
Step #2: Calculate Net Adjustment
Capitalizing 56% of Palantir’s $2.85B of SG&A and R&D means ~$1.6B is recorded as an investment instead of an expense.
Each year’s investment is then amortized evenly over the following 5 years, a fifth per year, beginning the year after it’s made. So the amortization in the latest 12 months comes from the previous five years’ investments.
For example, the investment from the 12 months through September 2025 is amortized for the first time, while the investment from the 12 months through September 2021 is amortized for the fifth and final time.
Using 56% of what Palantir actually spent in each of those years, the five investments add up to $5.04B, so the amortization comes to $1.01B:
Subtracting the amortization from the amount capitalized gives the net adjustment:
Net Adjustment = Amount Capitalized - Amount Amortized
where:
- Amount Capitalized = the year’s SG&A and R&D × the investment portion
- Amount Amortized = the previous five years’ capitalized amounts / the useful life
For Palantir, the net adjustment is $588.0M ($1,596.1M - $1,008.0M). That’s how much lower Palantir’s expenses are with its investments capitalized, so its operating income is $588.0M higher.
Step #3: Adjusted Results
Finally, here’s how these adjustments impact Palantir’s key financial metrics, margins, and valuation ratios:
Note: Table based on revenue of $7,288.3M for the 12 months to September 30, 2026, a market value of $415.4B (2,409.5M shares as of October 26, 2026, at the $172.40 close on November 11, 2026), and an EV of $404.8B.
With its intangible investments capitalized, Palantir’s operating income (EBIT) rises by the $588.0M net adjustment, from $3.33B to $3.91B, or 17.7%. That lifts its operating margin from 45.6% to 53.7%.
Palantir’s EBITDA rises by more. Since EBITDA is calculated before amortization, it goes up by the full ~$1.6B capitalized, from $3.36B to $4.95B, or 47.6%, and its EBITDA margin goes from 46.0% to 67.9%.
Palantir’s net income rises by the same $588.0M as its operating income, from $3.67B to $4.26B, or 16.0%, which lifts its net profit margin from 50.3% to 58.4%. As in Mauboussin and Callahan’s paper, net income rises by the full net adjustment, since reclassifying an expense in an analysis doesn’t change the taxes a company pays (Palantir’s effective tax rate was 1.4% in 2025).
Since Palantir had no debt as of September 30, 2026, its enterprise value (EV) is its market value minus its $10.6B of cash and marketable securities. The adjusted valuation metrics show similar improvements, with Palantir’s P/E ratio dropping from 113x to 98x (13.8% lower), its EV/EBIT from 122x to 103x (15.0% lower), and its EV/EBITDA from 121x to 82x (32.2% lower).
Testing Hulten’s Split
Since the 56% and the 5 years are estimates, it’s worth testing another split as well.
With Hulten’s split from the Microsoft example, I’d capitalize 64% of Palantir’s SG&A and R&D instead of 56%, amortizing R&D and G&A over 4 years and sales and marketing over 3 years, based on Hulten’s depreciation rates. Palantir’s adjusted P/E ratio would come out at 96x instead of 98x:
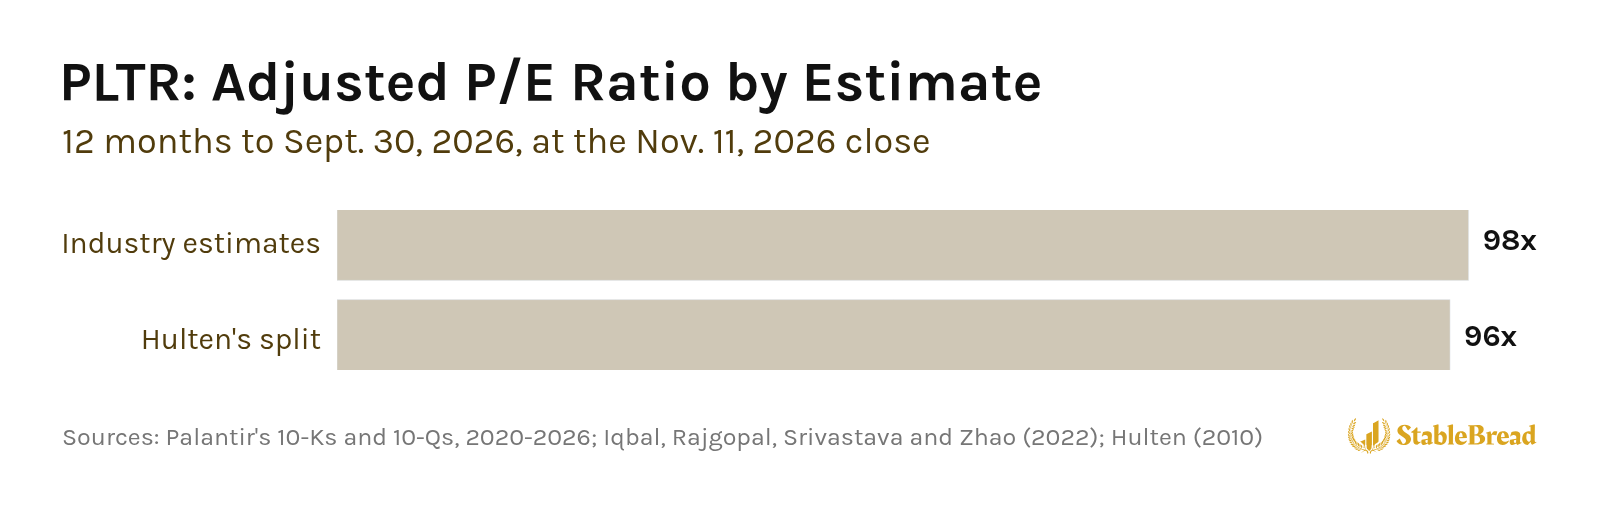
So for Palantir, the result doesn’t depend much on which estimates you use.
Either way, with its intangible investments capitalized, Palantir’s margins are higher, and its valuation multiples lower, than its reported numbers show. That suggests Palantir may be creating more value and might be more reasonably priced than what appears on the surface.
